
Global payment processing for businesses: All you need to know

Content Team

Summary
Global payment processing gives businesses the infrastructure to accept, send, convert, and settle payments across countries and currencies
You can use global payment processing to collect customer payments, pay suppliers and contractors, make international transfers, and manage cash across currencies
Common payment methods include international wire transfers, local bank transfers, cards, digital wallets, real-time payment networks, and multi-currency accounts
The benefits can include faster settlement, better visibility into international transactions, easier multi-currency management, and less manual payment work, depending on the infrastructure and provider you use. You still need to account for FX costs, transaction fees, fraud risks, compliance requirements, and potential payment delays
When choosing a global payment solution, look at pricing and FX transparency, supported currencies and payment methods, payment rail coverage, settlement speed, compliance and security, integrations, reporting, and scalability
One Aspire account to manage your business finances in one place.
Get a business account¹, issue corporate cards², manage expenses, and automate financial workflows, all from one powerful platform built for modern businesses.
For global businesses, cross-border payments can create operational challenges. Delays, hidden FX fees, failed transactions, and complex compliance rules often slow down payments to international suppliers, employees, or partners. Even small mistakes in overseas transfers can harm trust and disrupt operations. Global payment processing for businesses provides the infrastructure to send, receive, and manage payments across countries and currencies efficiently. In this guide, we explain what global payment processing is, how it works, its benefits and drawbacks, and the different types of businesses it can be used by.
What is global payment processing for businesses
Global payment processing is how businesses accept, send, convert, and settle payments across countries and currencies. It brings payment methods, banking networks, payment rails, FX, compliance checks, and settlement into connected workflows, so you can manage international transactions without relying on separate systems.
It can cover a range of business payments, including:
- Customer payments
- Supplier and contractor payouts
- Employee payments
- Marketplace disbursements
- Transfers between your own business accounts
What’s the difference between global payment processing, gateways, and processors
If you're managing payments across markets, understanding how gateways, processors, and global payment networks fit together can help you choose the right setup for your business.
You may not need to manage each layer separately. Some payment providers combine several of these functions into one solution, giving your business one place to manage more of the payment flow.
| Term | What it means | What it does in practice |
|---|---|---|
| Global payment processing | The broader infrastructure used to move and manage payments across countries and currencies | It can cover payment routing, currency conversion, compliance checks, settlement, reconciliation, and connections to different payment methods and networks |
| Global Payment gateway | The technology layer that securely captures and transmits payment information, particularly for online transactions | It connects the checkout experience with the systems needed to process the payment |
| Payment processor | The service that handles the communication needed to authorize and complete a transaction | It connects the merchant with payment networks and financial institutions as the transaction moves through the payment flow |
| Payment network or rail | The infrastructure that moves funds or transaction instructions between participants | Examples include card networks, ACH, wire networks, and local real-time payment systems |
How does global payment processing work
Global payment processing works by collecting payment details, checking the transaction for compliance and fraud risk, converting currencies when necessary, routing the payment through the appropriate payment rail, settling the funds, and reconciling the transaction.
However, not every payment follows every step in exactly this order. The workflow depends on the payment method, such as a card payment, bank transfer, wallet payment, local payout, or another payment method.
- A cross-border payment is initiated when a business or customer enters the recipient’s details and selects the required currency. This is typically instant, although incorrect payment details can lead to processing errors.
- The payment platform then captures key transaction information, including the amount, currency, sender, and destination country. This usually takes a few seconds but may be delayed by system or network connectivity issues.
- The transaction undergoes identity verification, AML screening, fraud detection, and other regulatory checks to ensure it meets applicable compliance requirements. These checks generally take seconds to a few minutes, but additional verification or regulatory requirements can extend the processing time.
- Where the sender and recipient use different currencies, the funds are converted using the applicable FX rate. This typically takes seconds, although FX rate updates or liquidity constraints may affect processing.
- The payment is routed through the appropriate payment rails, banking networks, or local partners to reach the recipient. Routing can take minutes to a few hours and may be affected by network congestion or intermediary bank processing.
- The funds are then delivered to the recipient’s bank account or wallet and settled in the local currency. Settlement can take anywhere from the same day to two business days, depending on banking hours, cross-border processing requirements, public holidays, the payment corridor, and intermediaries involved.
- Once the payment is completed, the business reconciles the transaction by recording it, matching the payment, and updating its financial records. This generally takes the same day to one day but may take longer when reconciliation is manual or transaction volumes are high.
Types of global payment methods and payment systems
Below is a more detailed comparison of the most common global payment methods US businesses rely on when operating internationally:
| Payment type | How it works | Best for | Speed | Cost structure | FX handling | Advantages | Limitations |
|---|---|---|---|---|---|---|---|
| International wire transfers | Funds move bank-to-bank through international correspondent networks, often via SWIFT. | Large B2B payments, supplier invoices, cross-border contracts | 75% of payments reach the beneficiary bank within 10 minutes and >90% within 1 hour | Flat wire fees plus possible intermediary bank charges | Often converted by a sending or intermediary bank; spreads may not be transparent | Widely accepted, reliable for high-value transfers | Higher fees, slower settlement, limited fee visibility |
| ACH and local bank transfers | Electronic transfers processed through domestic clearing systems, such as ACH in the US and local rails abroad. | Recurring vendor payments, payroll, and lower-cost transfers | 1–3 business days, varies by country | Lower transaction fees compared to wires | Converted at the platform or bank level if cross-currency | Cost-efficient, suitable for recurring payments | Limited to supported countries and local networks |
| Card payments (credit/debit) | Transactions processed through global credit card processing and acquiring banks. | Ecommerce, SaaS subscriptions, international customer payments | Near real-time authorization, settlement within days | Percentage-based processing fee plus cross-border fee | Currency conversion is often handled at checkout or by the acquirer | Global acceptance, familiar to customers, and fast authorization | Higher fees for cross-border transactions |
| Digital wallets | Customers pay using stored credentials within regional or global wallet platforms. | Mobile-first markets, cross-border ecommerce | Near instant | Wallet fees vary substantially by provider, transaction type, and market. | May convert at the wallet level or the merchant processor | Higher conversion in wallet-preferred markets | Adoption varies by country |
| Real-time payment networks | Instant bank transfers through modern domestic rails connected to cross-border infrastructure. | Marketplace payouts, gig worker payments, urgent transfers | Instant to minutes, where supported | Typically lower than wires, varies by corridor | FX handled by the platform at the time of transfer | Faster settlement improves cash flow | Not available in all countries |
| Cross-border payment gateways | Integrated payment layer enabling international checkout and settlement. | Global ecommerce expansion | Real-time authorization | Gateway fees plus processing and FX fees | Often converted at point of sale | Simplifies international checkout | Requires integration and compliance setup |
| Mass payout solutions | Bulk disbursement infrastructure to send funds to many recipients across countries. | Creator platforms, marketplaces, affiliate payouts | Varies by payout rail | Volume-based pricing models | FX locked per payout batch | Efficient for high-volume global payouts | Dependent on local payout availability |
Common global payment methods
Businesses can use different payment methods and payment rails to send, receive, or collect international payments, depending on the market, transaction type, currency, and recipient.
- Bank transfers: Move funds between bank accounts through domestic or cross-border payment networks. They are commonly used for business-to-business payments, supplier payments, payroll, and larger-value transactions.
- Cards: Credit, debit, and other card-based payments are widely used for consumer and business purchases, particularly online and at the point of sale. Card payments typically involve issuers, acquirers, payment processors, and card networks.
- Digital wallets: Allow customers or businesses to make payments using funds or payment credentials stored in a digital wallet. Wallets may connect to bank accounts, cards, or other funding sources, and availability varies by market and provider.
- Real-time payments: Enable account-to-account payments to be processed and funds made available within seconds where supported. They operate through specific real-time payment systems and can be initiated through banks, payment providers, wallets, or other channels.
- Local payment methods: Market-specific methods, including domestic bank schemes, mobile wallets, account-to-account payments, and other locally preferred options, can help businesses collect or make payments in individual markets.
Infrastructure businesses use to manage global payments
Businesses may use banking infrastructure, payment providers, fintech platforms, or combinations of these capabilities to manage the payment methods above.
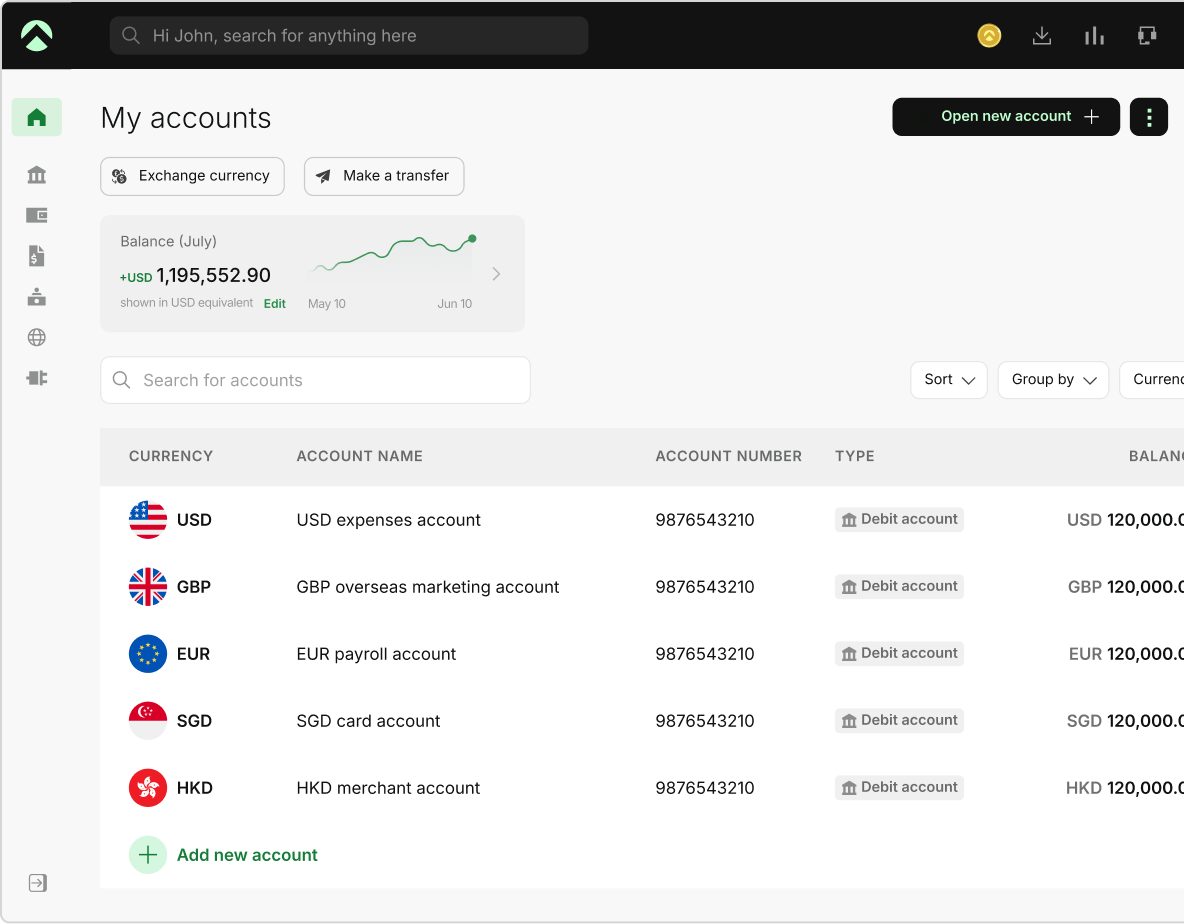
- Multi-currency accounts: Provide the ability to hold, receive, convert, and send funds in multiple currencies within a single account structure or platform. They can support international revenue collection, supplier payments, and treasury management, while allowing businesses to choose when to convert currencies. Availability, supported currencies, fees, and transfer capabilities vary by provider.
- Payment gateways: Provide the technology that connects a merchant’s checkout or payment interface with payment-processing infrastructure, securely transmitting payment information and supporting authorization and processing. A gateway is therefore infrastructure for accepting payments, not a payment method itself.
- Mass payout solutions: Allow businesses to initiate and manage payments to multiple recipients through a centralized workflow. They can support use cases such as supplier, contractor, marketplace, payroll, and customer payouts, using different underlying payment rails depending on the market and recipient.
- Payment APIs and orchestration: Connect business systems to payment providers, banks, and payment rails, allowing businesses to automate payment initiation, routing, reconciliation, and other workflows across markets.
What are the benefits of global payment processing for businesses
Global payment processing helps founders manage international payments with greater clarity, control, and fewer operational roadblocks.
1. Potentially reduce settlement delays
Faster payment processing can reduce delays when you receive money from customers in other markets. Getting funds sooner can improve cash flow, support day-to-day expenses, and give you more flexibility to reinvest in hiring, marketing, or product development.
2. Improve visibility into cross-border payment costs
International payments processing can involve multiple intermediaries and fees. Global payment systems can simplify how payments are routed, giving you clearer visibility into costs and helping you protect margins as your international payment volume grows.
3. See your FX costs before you pay
Exchange rate movements can affect how much you receive or spend across markets. Global payment platforms can show exchange rates and conversion costs before you make a transaction, helping you price with greater confidence and plan your cash flow more accurately.
4. Manage multiple currencies in one place
Managing separate accounts across markets can make it harder to see where your money sits. Multi-currency platforms let you hold, send, and receive different currencies from one system, giving you a clearer view of your global cash position.
5. Spend less time reconciling transactions
International payments can make reconciliation more complex, particularly when transactions involve different currencies and settlement times. Payment infrastructure can organize transaction data and connect with accounting or ERP systems, helping you reduce manual work and keep financial records accurate.
6. Build compliance into international payments
Cross-border payments need to meet local regulatory requirements. Global payment platforms can support checks such as KYC, KYB, sanctions screening, and AML monitoring, helping you manage international payments while meeting your compliance obligations.
What are the key challenges in global payment processing for businesses
As US businesses expand internationally, cross-border payments introduce complexity that doesn’t exist in domestic transactions. Without the right infrastructure, processing international payments can quietly erode margins, slow growth, and increase operational risk.
1. Time-consuming payment processes
Manual global payment workflows often require entering transaction data across multiple banking portals and systems, increasing the risk of incorrect account numbers, routing details, or payment amounts. These errors can result in failed transfers, overpayments, or funds being sent to the wrong recipient, while correcting them creates further delays and operational inefficiencies.
Finance teams must also perform manual reconciliation, increasing workload, slowing payment cycles, and diverting time from higher-value financial planning and analysis activities.
2. High transaction fees
Cross-border payments often involve multiple intermediaries such as correspondent banks, card networks, and processors. Each may add fees, while FX spreads and cross-border card charges further increase costs. Without centralized oversight, these layered expenses can significantly reduce profit margins.
3. Payment delays and late payouts
Inefficient workflows, slow payment rails, or processing bottlenecks can delay cross-border transactions. Late payouts may strain relationships with suppliers, contractors, and partners. They can also lead to penalties or missed early payment discounts, affecting operational efficiency and business credibility.
4. Regulatory and compliance requirements
Cross-border payments can trigger sanctions screening, identity verification, source-of-funds checks and other requirements imposed by banks, payment providers or applicable law. Requirements vary by jurisdiction, payment type and business activity.
5. Fraud and chargebacks
International transactions carry elevated fraud risk due to cross-border identity verification challenges and jurisdictional differences. Card-not-present transactions, especially in ecommerce, are more susceptible to fraud and chargebacks.
Disputes across countries can be more difficult to resolve, increasing loss exposure and operational strain.
What are the compliance and security measures for global payment processing for businesses
When businesses operate internationally, strong compliance and security controls are essential. Global payment systems include regulatory checks and technical safeguards to protect transactions, customer data, and access to financial networks.
Here are the compliance and security measures that global payment processing for businesses must meet:
1. Anti-Money Laundering (AML) monitoring
Financial institutions and other regulated payment providers may use automated AML programs to monitor transactions for suspicious activity and comply with applicable regulations, including the Bank Secrecy Act (https://www.fincen.gov/resources/statutes-and-regulations/bank-secrecy-act) (BSA) where applicable.
These tools analyse factors such as transaction volume, frequency, geography, and behavioural patterns to identify anomalies, with flagged transactions subject to further review.
2. Sanctions screening and restricted party checks
Cross-border transactions are screened against US sanctions lists such as the U.S. Treasury’s Office of Foreign Assets Control (OFAC), Specially Designated Nationals (SDN), and global restricted-party databases.
This ensures payments do not involve sanctioned individuals, organizations, or jurisdictions. Automated sanctions screening helps businesses avoid prohibited transactions and reduces the risk of regulatory penalties.
3. PCI DSS compliance
Businesses accepting card payments must comply with the Payment Card Industry Data Security Standard (PCI DSS).
Global payment processors may maintain PCI DSS-compliant infrastructure to protect cardholder data during storage, transmission, and processing. However, outsourcing payment processing does not eliminate the merchant’s PCI DSS responsibilities; merchants remain responsible for ensuring their providers are compliant and understanding their respective shared responsibilities.
4. Data encryption and tokenization
Sensitive payment information is encrypted both in transit and at rest. Tokenization replaces raw card or account numbers with secure tokens during processing.
This significantly reduces the risk of data breaches and protects customer financial information throughout the transaction lifecycle.
5. Fraud detection and real-time risk scoring
Many payment platforms use behavioral analytics and machine learning to assess transaction risk before authorization.
Signals such as device fingerprinting, geolocation inconsistencies, and transaction velocity help identify suspicious activity and reduce fraud risks in international payments.
How global payment providers differ
For US businesses expanding internationally, global payments can be managed through different provider models, including banks, fintech payment platforms, and combinations of the two. Rather than treating these as separate alternatives, businesses should compare the capabilities each solution offers across payment speed, cost, currency coverage, integrations, visibility, and scalability.
| Category | Banks and bank-led solutions | Fintech payment platforms | Bank-fintech combinations |
|---|---|---|---|
| Payment infrastructure | May provide direct access to payment networks, wires, real-time payments, FX, and other payment services. | Often connect businesses to multiple payment rails through their own technology and underlying banking partners. | Combine banking infrastructure with fintech technology, payment orchestration, and other digital capabilities. |
| Speed | Speed depends on the payment method, corridor, currency, cut-off times, and correspondent institutions. | May automate routing and settlement across supported payment methods, with speed varying by corridor and rail. | Can combine established banking rails with technology designed to streamline payment workflows. |
| Multi-currency capabilities | May offer multi-currency accounts, FX services, and international cash management, depending on the institution and market. | Often provide centralized tools to receive, hold, convert, and send multiple currencies where supported. | Can combine bank-provided accounts and FX services with centralized fintech interfaces and workflows. |
| Integrations | Many banks offer APIs and digital integration options, although capabilities vary by institution and product. | Typically emphasize APIs and integrations with ecommerce platforms, ERP systems, marketplaces, accounting software, and internal systems. | May provide fintech APIs alongside banking products and infrastructure. |
| Visibility and reporting | Provide statements, transaction histories, payment tracking, and cash-management tools. | Often centralize payment status, balances, currencies, fees, and transaction reporting in a single interface. | Can combine banking records and reporting with a centralized technology layer. |
| Scalability | Can support high payment volumes and broader banking requirements, although international expansion may involve additional accounts, products, or banking relationships. | May allow businesses to add payment methods, currencies, and markets through an existing technology and integration framework. | Can provide banking capacity alongside technology designed to support expansion across payment methods and markets. |
| Best suited to | Businesses that need banking, treasury, FX, credit, and payment services within an established financial relationship. | Businesses prioritizing digital workflows, payment integrations, centralized visibility, and access to multiple payment methods or markets. | Businesses that need banking infrastructure while also seeking specialized technology and payment capabilities. |
What to look for when choosing a global payment processing solution for businesses
For US businesses expanding internationally, the right partner should reduce friction, support scale, and simplify the global payment process of transferring funds abroad. Here are the key factors to evaluate when choosing a global payment service:
1. Transparent pricing and FX structure
Look beyond headline fees. Ask how FX rates are determined, whether markups are disclosed upfront, and if intermediary bank charges apply.
Transparent pricing helps you forecast costs accurately and avoid margin erosion at scale.
2. Multi-currency support
A strong system for global payment processing for businesses should allow you to send, receive, and hold multiple currencies.
The ability to manage balances without converting every transaction immediately gives you more control over cash flow and currency exposure.
3. Payment rail coverage
Evaluate which countries, currencies, and local payment methods the platform supports.
Consider whether it:
- Connects to local clearing systems.
- Supports cards.
- Supports ACH equivalents.
- Supports wallets.
- Supports real-time payment networks.
Broader coverage reduces the need for multiple providers.
4. Settlement speed and reliability
Understand typical settlement times for your most important corridors.
Faster settlement improves working capital and operational agility. Consistency matters just as much as speed.
5. Compliance and security standards
Confirm that the provider maintains strong KYC, KYB, AML monitoring, and sanctions screening processes.
Look for:
- PCI DSS compliance
- Data encryption
- Multi-factor authentication
- Scalable compliance infrastructure
Compliance infrastructure should scale with your business.
6. API capabilities and integration
If you operate in ecommerce, SaaS, or marketplaces, integration matters.
Review:
- API documentation
- Webhook support
- Compatibility with accounting systems
- Compatibility with ERP systems
Seamless integration reduces manual work and supports automation.
7. Reporting and visibility
You should have real-time access to:
- Transaction data
- FX rates
- Settlement status
- Multi-currency balances
Strong reporting tools simplify reconciliation and improve financial oversight.
8. Scalability and global footprint
Choose a global payment solution designed for international growth.
Consider whether it supports new markets without requiring separate banking relationships or complex setup processes. Your payment infrastructure should grow with you.
9. Reliability and customer support
Payment issues can interrupt sales, supplier payments, and other time-sensitive transactions, so reliability matters alongside features and pricing. Evaluate uptime, incident communication, support availability, and how quickly the provider can resolve failed or delayed transactions.
Conclusion
Global payment processing helps you manage transactions across countries and currencies from connected payment infrastructure. By bringing payment methods, payment rails, FX, compliance, settlement, and reconciliation together, it can reduce manual work and give you clearer visibility over global payments.
The right solution depends on where you operate, which currencies and payment methods you need, and the volume and type of transactions you process. Compare FX rates and fees, payment coverage, settlement times, compliance and security controls, integrations, reporting, and scalability before choosing a provider.
If you’re looking to manage global payments from one platform, an Aspire1 multi-currency accounts supports multi-currency* accounts across 13 currencies and international payments in 98+ currencies across 130+ countries. Businesses can make same-day payments to 40+ currencies where supported, with FX rates starting from 0.22% above mid-market rates. Aspire1 also brings expense management and accounting integrations, including QuickBooks and Xero, into the same financial platform.
Frequently Asked Questions
Settlement time depends on the payment method and corridor. Traditional international wires can take 2–5 business days, especially if intermediary banks are involved. Global payment platforms may offer same-day or near real-time settlement in supported regions, improving cash flow predictability for US businesses.
Global and international payment processing are closely related, but they describe different scopes. International payment processing typically refers to transactions between countries. Global payment processing takes a broader view, covering how a business manages payments across multiple markets, currencies, payment methods, and payment rails.
Cross-border payments often include additional FX spreads and international processing fees. However, platforms built for global transactions typically provide transparent pricing and competitive exchange rates, helping reduce unnecessary intermediary charges compared to traditional banking setups.
Not necessarily. Many global payment systems provide multi-currency accounts that allow you to hold, send, and receive funds in different currencies from one centralized platform. This eliminates the need to open separate bank accounts in every country you operate in.
Global businesses can use a mix of payment methods, including international wire transfers, ACH and local bank transfers, cards, digital wallets, real-time payment networks, and multi-currency payment accounts. The right mix depends on where you operate, the currencies you handle, and how your customers and suppliers pay you.
Reputable providers embed KYC, KYB, AML monitoring, sanctions screening, PCI DSS compliance, and data encryption into their infrastructure. These built-in controls help US businesses meet regulatory requirements while protecting customer data and reducing fraud risk.
Sources
- https://www.bis.org/publications/paper-167-cross-border-payment-technologies-innovations-and-challenges + (March 11, 2026)
- https://www.fsb.org/2021/10/targets-for-addressing-the-four-challenges-of-cross-border-payments-final-report/ + (October 13, 2021)
- https://www.fsb.org/work-of-the-fsb/financial-innovation-and-structural-change/cross-border-payments/g20-targets-for-enhancing-cross-border-payments-2/ + (March 21, 2025)
- https://www.fsb.org/work-of-the-fsb/financial-innovation-and-structural-change/cross-border-payments/ + (October 9, 2025)
- https://www.bis.org/publications/payments-without-borders + (February 18, 2020)
- https://www.swift.com/payments/how-long-does-swift-payment-take + (September 9, 2026)
- https://www.nacha.org/content/how-ach-payments-work + (September 9, 2026)
- https://www.nacha.org/news/significant-majority-ach-payments-settle-one-business-day-or-less + (August 28, 2023)
- https://www.pcisecuritystandards.org/faqs/does-pci-dss-apply-to-merchants-who-outsource-all-payment-processing-operations-and-never-store-process-or-transmit-cardholder-data/ + (September 9, 2026)
- https://www.fincen.gov/resources/statutes-and-regulations/bank-secrecy-act + (September 9, 2026)
- https://ofac.treasury.gov/sanctions-list-service + (September 9, 2026)
- https://ofac.treasury.gov/sanctions-list-search-tool + (September 9, 2026)
- https://www.bis.org/publications/service-level-agreements-cross-border-payment-arrangements + (April 29, 2024)
- https://www.bis.org/speeches/20240826-cross-border-payments-unlocking-new-frontiers + (August 26, 2024)
- https://aspireapp.com/us/global-payments + (September 9, 2026)
- https://aspireapp.com/us/pricing + (September 9, 2026)
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our ’Terms of Service’ and ’Pricing’ pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Content Team
Aspire editorial
Content team at Aspire is a society of seasoned writers & experts specialising in finance, technology and SaaS space. With 50+ years of collective experience, they help make business finance more profitable for readers. They write about finance tools, finance insights, industry trends, tactical guides to grow your business & also all things Aspire.
Aspire Launchpad
Supercharge your finance operations with Aspire
Find out how Aspire can help you speed up your end-to-end finance processes from payments to expense management.

Latest articles
QuickBooks vs Xero: Key differences, costs and which is better
QuickBooks vs Xero compared on features, pricing, users, reporting, and ease of use. See which accounting software is a better fit for your business.
How general liability vs professional liability insurance works in the US
Small business guide to general liability insurance. Learn about costs and coverage, if you need it, and how to choose the right policy.
Best multi-currency business accounts in the US for 2026
Compare the best multi-currency business accounts in the US for 2026. Explore fees, FX costs, currencies, holding, receiving options, and key features.