
How to open a US bank account for non-residents: requirements, options, and steps
Bintang Lestada

Summary
You can get one of three things as a non-resident: a personal account, a business account, or a USD receiving account. Where you live and whether you have a US company decide which
Remote applications are possible with some providers, but approval isn't guaranteed. Every application still goes through identity and compliance checks
An EIN identifies your company. It doesn't replace owner checks, so expect to share a passport, proof of address, and ownership details too
Banks and fintech providers set different rules. Check that a provider accepts applicants from your country before you start
A $0 monthly fee can hide FX markups and wire fees. Compare what you'll pay to actually use the account
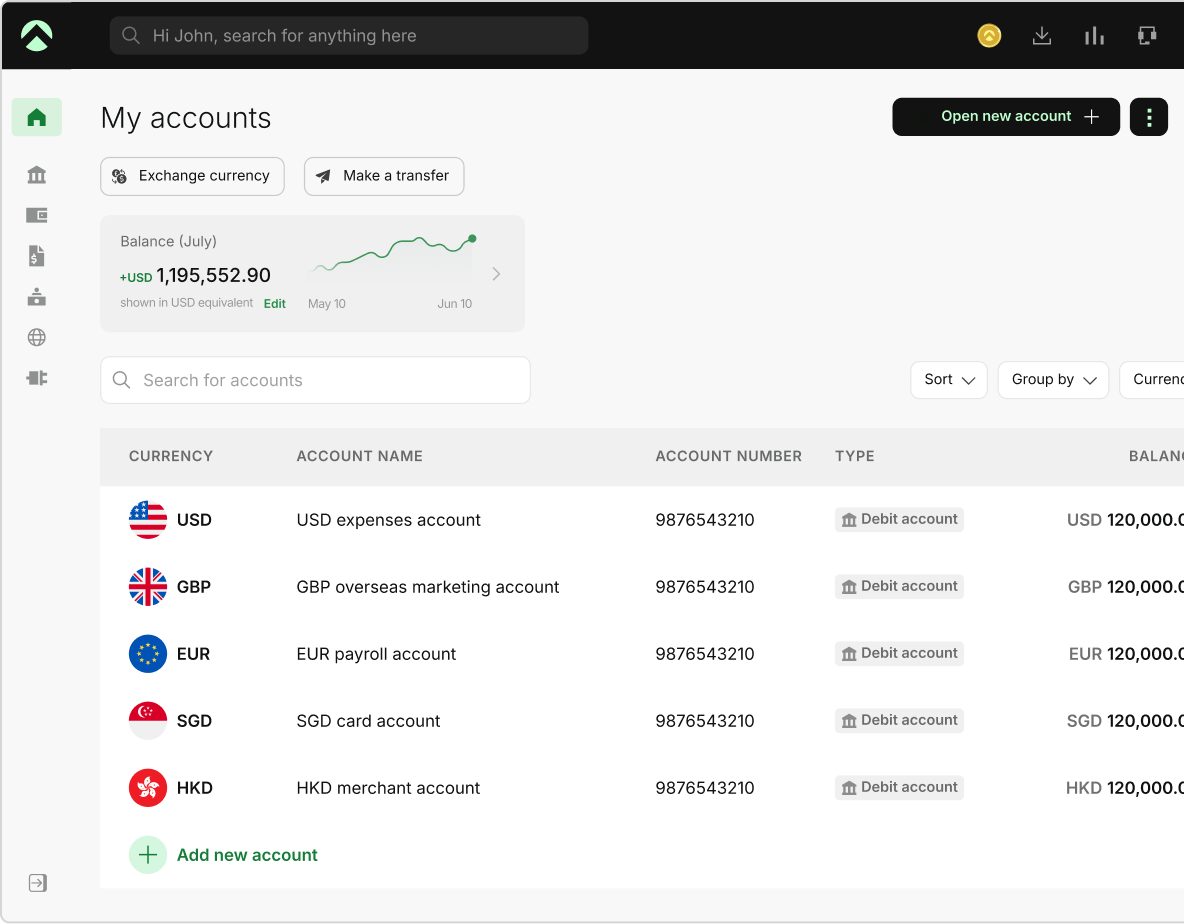
One Aspire account to manage your business finances in one place.
Get a business account¹, issue corporate cards², manage expenses, and automate financial workflows, all from one powerful platform built for modern businesses.
If you earn in USD or pay US bills, a US bank account removes a lot of friction. That's true whether you've moved to the US for work or study or run a business from another country.
You don't need to be a US citizen or permanent resident to open a non-resident bank account in the USA. What you can open is a different question, and the answer mostly comes down to where you live and whether you have a US company. The right bank account for non-US residents also depends on whether you need personal banking, business banking, or simply a way to receive USD.
Can a non-resident open a US bank account?
Yes. Some traditional banks, fintech providers, and cross-border payment providers accept non-residents.
If you live in the US
If you're in the US to study or work, you can usually apply for a personal account at a traditional bank. Expect to show a passport or other photo ID and proof of your US address. No SSN? Some banks accept an ITIN instead. Others ask you to fill in IRS Form W-8BEN.
If you live outside the US
Applying from abroad is harder, because many traditional banks ask for a US address or a branch visit. Remote options usually fall into two groups: a business account for an eligible US entity, which many fintech providers support online, and a USD receiving account from a cross-border payment provider.
Why open a US bank account as a non-resident?
A US account lets employers, clients, and payment processors such as Stripe and PayPal pay you directly through ACH or direct deposit. You can pay rent, suppliers, and contractors with domestic transfers instead of international wires , and you can hold USD and convert only when you choose to.
On its own, a US account won't build a US credit history. It does keep your records in one place, which helps with bookkeeping and later with lenders.
Account types available to non-residents
Personal bank account
Some banks open personal accounts for non-residents. Expect to show ID and proof of address, and possibly tax or immigration documents. Many also want you to come into a branch.
Business bank account
If you own a US LLC or corporation, you can apply for a business account in the company's name. The provider will look at your ownership, country of residence, and what the business does before approving it.
USD receiving account
Some providers give you US routing and account details for getting paid in USD. Freelancers and cross-border businesses use these often, but they aren't always full deposit accounts in your name.
What are your US non-resident bank account options?
The right route depends on whether you need a full bank account, business banking, or US payment details for receiving USD.
| Account/provider type | What it generally provides | Who provides it | Things to consider |
|---|---|---|---|
| Traditional US bank account | Deposit account with ACH, domestic wires, debit cards, and other banking services | A licensed US bank | May require stricter eligibility checks and, in some cases, an in-person application |
| Fintech business account | Business banking features such as payments, cards, expense management, and USD banking through a partner bank | A fintech platform working with licensed banking partners | Check which partner bank holds your funds and whether you meet the provider's eligibility requirements |
| Cross-border payment account | Receive, hold, and send funds in multiple currencies, including USD | A licensed payment institution or financial services provider | Some don't require a US entity, but they may offer fewer banking features than a traditional bank |
| Virtual USD receiving account | US routing and account details for receiving USD payments | A payment or financial services provider | US receiving details don't necessarily mean you have a traditional US deposit account in your own name |
| International or correspondent banking | Access to US banking services or payment capabilities through relationships between international and US banks | An international bank and its US banking partners | Availability depends on the bank, your location, and the services it provides |
Every provider has to verify you. KYC and AML rules require it, so expect checks on your identity, your documents, and, for a business, it can include beneficial owners’ information.
Which US account route is right for you
Use the table below to find the best way to open a US bank account as a non-resident in your situation.
| If you are… | Best account route | What you'll typically need | What to check |
|---|---|---|---|
| Founder with a US LLC or corporation | US business bank account | EIN, company formation documents, owner verification | Some providers exclude certain industries |
| Freelancer or contractor receiving USD | USD receiving account | Identity verification and, in some cases, business details | Whether it's a full deposit account |
| International student or employee living in the US | Personal US bank account | Passport, proof of address, and any required tax or immigration documents | Many banks need a branch visit |
| Business operating across multiple countries | Multi-currency business account | Business verification and owner identification | Compare supported currencies, FX rates, and international payment capabilities |
| Planning to incorporate in the US | Form your US business entity first, then apply for a business account | Company formation documents and EIN | You can't apply until the entity exists |
Personal vs business US account: which do you need?
When opening a US bank account for non-residents, the personal vs business choice comes down to whose money it is. Salary, rent, and day-to-day spending belong in a personal account. Revenue and expenses that run through a US company belong in a business account.
| Factor | Personal account | Business account |
|---|---|---|
| Account owner | An individual | A registered business entity, LLC or C-corp, or an eligible sole proprietor |
| Primary use | Personal banking, salary, and everyday expenses | Business revenue, vendor payments, payroll, and operating expenses |
| Tax identifier | SSN, ITIN, or other accepted documentation may be requested, depending on the provider | An EIN is commonly required for a US business entity, while owners and control persons still undergo identity verification |
| Identity verification | Government-issued ID, residential address, and any required tax or immigration documents | Government-issued ID, residential address, beneficial ownership, and control-person verification |
| US address | Commonly required by many traditional banks | Requirements vary by provider |
| Remote application | Available with some providers but often limited for non-residents | More widely available through selected fintech providers, subject to eligibility and compliance checks |
| Best suited for | Individuals living, working, or studying in the US | Founders and businesses operating through an eligible business entity |
If you're a founder based outside the US and already operate through a US LLC or corporation, a US business bank account for non-residents is often easier to get than a personal account, because many traditional banks ask personal applicants for a US address or an in-person visit. If you live in the US for work or study, a personal account may be the simpler starting point.
What account details do you get, and does the US use IBAN?
No. US bank accounts don't use IBANs. Instead, they use an ABA routing number and an account number to send and receive payments.
Here's what you'll typically receive when you open a US bank account:
- ABA routing number: A 9-digit number that identifies your bank. You'll use it for ACH transfers, direct deposits, and most domestic wire transfers
- Account number: Your unique account identifier used to receive and send funds
If an international customer, supplier, or platform asks for an IBAN, give them these details instead:
- Your bank's SWIFT/BIC code
- Your ABA routing number
- Your account number
With these, they can send you an international wire.
What documents do non-residents need to open a US account?
Business accounts need more paperwork than personal ones, because the provider checks the company as well as you. Here's what providers commonly ask for. Your provider may ask for more.
| Document | Personal account | Business account |
|---|---|---|
| Government-issued ID | Commonly required, usually a passport | Commonly required for all beneficial owners and control persons |
| Residential address | Commonly required | Commonly required for business owners and control persons |
| US address | May be required by some providers | Provider-specific. A registered agent address alone may not satisfy requirements for an operating business address or owner address. |
| Tax identifier | An SSN, ITIN, or other accepted documentation may be requested, depending on the provider | An EIN is commonly required for US business entities. Owners may still need to provide additional identification. |
| Business formation documents | Not applicable | Commonly required, such as Articles of Organization or Articles of Incorporation |
| Ownership information | Not applicable | Commonly required to verify beneficial owners and control persons |
| Proof of business activity | Not applicable | May be requested, such as a business website, invoices, contracts, or other supporting documents |
SSN vs ITIN vs EIN: What do non-residents need?
These three numbers do different jobs. SSNs and ITINs identify people. An EIN identifies a business. Personal accounts usually ask for an SSN or ITIN. Business accounts ask for the company's EIN.
| Identifier | Who it applies to | Primary purpose | When a provider may request it |
|---|---|---|---|
| SSN (Social Security Number) | US citizens, permanent residents, and certain work-authorized individuals | Individual identification and tax reporting | Commonly requested for personal accounts and by some traditional banks |
| ITIN (Individual Taxpayer Identification Number) | Individuals who aren't eligible for an SSN but have US tax reporting obligations | Individual tax identification | May be accepted by some providers in place of an SSN, depending on the account type |
| EIN (Employer Identification Number) | US business entities | Business tax identification | Commonly required when opening a business account for an eligible US entity |
Can you open a US bank account without an SSN?
Yes, depending on the account type and provider. For business accounts, some providers let eligible non-residents apply without an SSN. The company's EIN may satisfy the business's tax identification requirement, but the provider will still verify the owner's identity and may request other personal information or documents. For personal accounts, some traditional banks accept an ITIN in place of an SSN. The identity checks still apply in both cases.
How much does a US bank account for non-residents cost?
Some providers advertise a free US bank account for non-residents. "Free" usually means no opening fee and no monthly fee. You can still pay for wires, currency conversion, and extra cards, so check each line below before you choose.
| Cost | What to expect |
|---|---|
| Account opening fee | Many providers don't charge an account opening fee, but policies vary |
| Monthly maintenance fee | Some providers charge one unless you meet a balance or activity condition |
| Minimum opening deposit | Some providers don't require an opening deposit, while others may have minimum funding requirements |
| ACH transfers | Basic ACH payments are often included, but fees can vary depending on the provider and transaction type |
| Domestic and international wire transfers | Fees may apply for sending or receiving wire transfers, especially cross-border payments |
| FX markups | If you regularly convert currencies, FX spreads can become one of your biggest banking costs |
| Cards and premium features | Physical cards, additional users, or premium plans may come with separate charges |
Which US banks open accounts for non-residents?
Several large US banks take non-resident customers. Most of them expect you to live in the US or come into a branch.
Bank of America
Bank of America offers its Advantage Banking accounts to customers who are new to the US, with separate guidance for international students. To open a checking account, you confirm your eligibility, gather the required documents, and book an appointment with a specialist at a financial center.
Chase
Chase lists government-issued photo ID (such as a passport), proof of a US address, and in some cases an opening deposit as typical requirements. If the bank asks for an SSN and you don't have one, you can use an ITIN instead.
PNC Bank
PNC says non-residents can open an account without an SSN. The bank accepts an ITIN or another ID number instead, and if you have neither, you'll fill in IRS Form W-8BEN. PNC also asks for photo ID and proof of address, and doesn't require an opening deposit.
U.S. Bank
U.S. Bank's online application for personal checking is open to legal US residents aged 18 or older with a Social Security number. Branch applications are also available and require valid government ID. U.S. Bank doesn't list non-resident requirements on its checking page, so confirm your eligibility with the bank before visiting.
If you live outside the US and can't visit a branch, traditional banks are usually harder to open remotely. Fintech providers and USD receiving accounts are the more practical options in that case.
US account providers for non-residents compared
The table groups providers by account type so you can compare like with like.
| Provider | Account type | Do you need a US entity? | Best suited for | Main limitation |
|---|---|---|---|---|
| Aspire | Fintech business account | Yes | Cross-border businesses and founders managing international payments | Subject to country and eligibility requirements |
| Mercury | Fintech business account | Typically yes | US startups and venture-backed companies | Available only to eligible businesses and countries |
| Relay | Fintech business account | Typically yes | Small businesses with multiple users and expense management needs | Requires an eligible US business entity |
| Revolut Business | Fintech business account | Depends on market | Businesses operating across multiple countries | Availability varies by country |
| Wise Business | Cross-border payment account | Not always. A US entity may be needed for a US business account, while some providers let eligible founders receive and manage USD without one | Freelancers and businesses receiving and sending multiple currencies | May not provide all the features of a traditional US bank account |
| Payoneer | Cross-border payment account | Not always | Exporters, freelancers, and marketplace sellers | Banking functionality varies by region and account type |
| Bank of America | Traditional bank | Not necessarily | Individuals and businesses that can visit a branch | Accounts are opened with a specialist at a financial center |
| Chase | Traditional bank | Not necessarily | Customers looking for a full-service banking relationship | Proof of US address commonly required |
| Citibank | Traditional bank | Not necessarily | International customers with access to Citi's global network | Eligibility and onboarding requirements vary by location |
| PNC Bank | Traditional bank | No, for personal accounts | Non-residents living in the US, including those without an SSN | Proof of address required |
Which option fits your situation?
Students and employees living in the US
A personal checking account at a traditional bank is usually the most practical route, since you can visit a branch and provide a US address. If you don't have an SSN, ask whether the bank accepts an ITIN or Form W-8BEN.
Individuals living outside the US
Opening a personal account at a traditional bank from abroad is difficult, because many banks ask for a US address or a branch visit. A USD receiving account from a cross-border payment provider can be a practical option. If you already bank with an international institution, also ask whether it can help you access US banking services.
Freelancers and marketplace sellers receiving USD
A USD receiving account lets you receive ACH payments and marketplace payouts without forming a US entity. Check whether the provider supports the platforms you sell on.
Founders with a US LLC or corporation
A fintech business account can be a practical option, since many fintech providers accept remote applications from eligible US entities. Compare country eligibility, supported industries, payment features, and fees before you apply.
Businesses operating across multiple countries
Look for a multi-currency business account that lets you hold, convert, and pay in several currencies from one place. Aspire1 is built for this, with multi-currency balances*, cross-border payments, and spend management for eligible businesses.
How to open a US bank account online for non-residents
Here's the usual order. Preparing documents and choosing your provider differ for personal and business accounts. If you're comparing online banks for non-residents, check whether they accept applicants from your country and whether they offer a true bank account or a fintech/payment account.
Step 1: Choose the right account route
Decide between a personal account, a business account, and a USD receiving account. The route table above will point you to one.
Step 2: Check your eligibility
Before applying, confirm that the provider supports:
- Your country of residence
- Your business entity, if you have one
- Your industry or business activities
- Your ownership structure
Step 3: Prepare your documents
For a personal account, you'll typically need a passport, proof of address, and an SSN, ITIN, or other accepted identifier. For a business account, you may also need your company's formation documents, such as Articles of Organization and an operating agreement, plus your EIN confirmation letter, and identity documents for each beneficial owner. Some providers also ask for proof of business activity, such as a website, invoices, or contracts.
Step 4: Choose your provider
If you can visit a US branch, a traditional bank is an option for a personal account. If you're applying from abroad, compare fintech and cross-border payment providers, or ask your international bank whether it can help you access US banking services through its US banking relationships.
Step 5: Submit your application
Complete the application online or at a branch. Simple applications can clear quickly, but complex ones can take weeks, so don't leave this until the week you need the account.
Step 6: Respond to any verification requests
If the provider asks for more documents or a clarification, reply quickly. The review usually stops until you do.
Step 7: Fund and test your account
Make your first deposit if the provider requires one, then send a small test payment before you share your account details with employers, clients, or customers. Minimum deposit rules vary, and some providers, such as Aspire1, don't require one.
Step 8: Connect your payment integrations
Add your US routing and account number to your payroll, payment processor, or marketplace accounts, such as Stripe or PayPal.
Do you need a US LLC to open a US bank account as a non-resident?
If you plan to open a US bank account for an LLC as a non-resident, you'll need to form the LLC and get its EIN before you apply, since most business accounts are only available to registered entities. However, not every non-resident needs to form an LLC. If you only need to receive USD or want a personal account, you don't need one.
Keep in mind that forming a US LLC also creates legal, tax, and ongoing reporting obligations. Form one only if it makes sense for your business beyond banking.
How long does it take to open a US bank account as a non-resident?
Expect anywhere from a few days to several weeks. Most of that time goes into gathering documents and waiting for compliance review. While some applications move quickly, others take longer if additional verification is needed.
| Stage | Typical timeframe | What can affect the timeline? |
|---|---|---|
| Document preparation | A few days to several weeks | Gathering identity documents, obtaining an EIN if you need one, or completing business formation before applying |
| Application submission | Usually completed in one session | Whether you're applying online or at a branch, and whether all required information is ready |
| Compliance review | A few business days to several weeks | Additional identity verification, document mismatches, beneficial ownership checks, business activity reviews, or source-of-funds requests |
| Account activation or card delivery | Varies by provider | Account details often arrive on approval while physical cards take longer |
Note: No provider can guarantee approval within a fixed timeframe.
Common reasons non-resident applications are delayed or rejected
Most delays come down to documents that don't match, missing information, or eligibility and compliance checks.
1. Inconsistent identity details
Name discrepancies between your passport, LLC formation documents, tax IDs, or application form are one of the most common reasons for additional verification or rejection. Verify that your legal name, date of birth, and address are consistent across every document before submitting your application.
2. Problematic or mismatched addresses
Providers often won't accept a registered agent address , PO box, or virtual mailbox as your principal business address, especially when it doesn't match your formation or tax records.
3. International phone numbers
Some providers ask for a US phone number for two-factor authentication, and some don't accept VoIP numbers such as Google Voice. Check the provider's requirements before you start.
4. Compliance reviews and account freezes
Providers monitor transactions on an ongoing basis. Operating in industries such as crypto, firearms, and cannabis, or receiving large, irregular transfers, can trigger reviews or temporary restrictions, especially on newer accounts.
5. Transfer limits on new accounts
Some providers set daily or monthly limits on new accounts, which may increase as you build account history. Factor this into your cash flow planning.
6. Sanctions and high-risk jurisdictions
Providers usually decline applicants from sanctioned or high-risk countries, and businesses with owners on watch lists, whatever the business model.
7. Business model and risk profile
Industries with higher AML or chargeback risk face tighter scrutiny and more rejections. These include some crypto businesses, gambling, firearms, and unlicensed financial services.
8. Missing or unclear beneficial owner information
Providers may need to verify each beneficial owner. If you can't clearly document who owns the company and where they live, compliance teams will typically say no.
Before you reapply, check that names, addresses, ownership details, and business activity match across all your documents.
How Aspire supports eligible international businesses
A US account covers how you receive USD. Running a business across borders also means paying contractors in their local currencies, managing expenses across entities, and keeping track of cash across several platforms.
Aspire1 offers USD business accounts for eligible businesses, along with cross-border payments, multi-currency balances*, expense management, and financial reporting in one platform.
When Aspire may be a good fit for non-resident founders
Aspire1 is a financial technology company, not a bank. Banking services are provided by Aspire's licensed banking partners. Eligibility and available features vary by country, business type, and applicable regulations.
Aspire may suit your business if you:
- Operate through an eligible business entity
- Send and receive domestic and international business payments
- Manage expenses, approvals, and corporate cards across your team
- Work with multiple currencies* and want to manage them from one platform
When another option may be more suitable
Another provider may be a better fit if you:
- Need a personal US bank account rather than a business account
- Prefer in-person branch banking or frequent cash deposits
- Don't meet Aspire's country, entity, or eligibility requirements
- Need banking products or services that aren't currently supported by Aspire1
If you need to manage cross-border payments and expenses as well as hold USD, check whether your business is eligible for Aspire1 and compare its features with other providers before you apply.
Choose the right US account for your situation
Choosing the best US bank account for non-residents starts with four questions:
- What type of account do you need?
- Can you meet the provider's entity, identity, and address requirements?
- Does the account support the payment methods, currencies, and platforms you rely on?
- Where do you live?
Confirm current requirements with the provider before you apply.
Frequently Asked Questions
Yes, but your options are narrower than if you live in the US. Many traditional banks ask for a US residential address or an in-person visit, so if you're based abroad, you can look at business accounts for an eligible US entity, USD receiving accounts from cross-border payment providers, or US banking services available through an international bank. If you live in the US for work or study, a personal account at a traditional bank is often easier to get.
Yes, if you have an eligible US business entity or choose a provider that accepts applicants from India. The provider will still check your business structure, ownership, industry, and documents.
There isn't one best bank for every non-resident. If you live abroad and own a US company, a fintech business account may be an option to consider. If you live in the US and can visit a branch, a traditional bank may also be an option.
Yes, with some providers. If you're looking for a US bank account for non-residents online, fintech and cross-border payment providers are more likely to support a fully remote application, while many traditional banks ask you to verify your identity at a branch.
Yes, if your application is approved. Depending on the provider and account type, you may receive a debit card, corporate card, prepaid card, or another business payment card. Card availability and delivery countries vary by provider.
Sometimes. Many traditional banks ask for proof of a US residential address for personal accounts. Some fintech and cross-border payment providers accept a foreign residential address, though business applicants may also need a valid business address for the entity, and a registered agent address alone may not be accepted.
Sources
- https://info.bankofamerica.com/en/international/us-bank-account-non-residents , 4 Oct 2026
- https://www.chase.com/business/checking/checklist/llc , 4 Oct 2026
- https://www.usbank.com/bank-accounts/checking-accounts.html , 4 Oct 2026
- https://www.irs.gov/tin/itin/individual-taxpayer-identification-number-itin , 28 Oct 2025
- https://www.irs.gov/forms-pubs/about-form-w-8-ben , 2 Oct 2026
- https://www.irs.gov/businesses/small-businesses-self-employed/get-an-employer-identification-number , 19 Aug 2026
- https://www.federalregister.gov/documents/2016/05/11/2016-10567/customer-due-diligence-requirements-for-financial-institutions , 2 May 2016
- https://support.mercury.com/hc/en-us/articles/28770467511060-Eligibility , 4 Oct 2026
- https://relayfi.com/hc/en-us/articles/10239600121748-Prohibited-Countries/ , 11 Aug 2026
- https://wise.com/us/business/ (https://wise.com/us/business/), 4 Oct 2026
- https://www.payoneer.com/receive-payments/ , 4 Oct 2026
- https://help.revolut.com/en-US/business/help/setting-up-an-account/is-my-business-eligible/what-country-of-residence-is-eligible-to-open-a-revolut-business-account/ , 4 Oct 2026
- https://aspireapp.com/en-us/business-account , 4 Oct 2026
- https://aspireapp.com/en-us/global-account , 4 Oct 2026
- https://aspireapp.com/en-us/global-payments , 4 Oct 2026
- https://aspireapp.com/en-us/corporate-card , 4 Oct 2026
- https://aspireapp.com/en-us/expense-management , 4 Oct 2026
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our ’Terms of Service’ and ’Pricing’ pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Bintang Lestada
Writer
Bintang is a seasoned writer specialising in fintech, agtech, politics, and pop culture. With a writing history at VICE ASIA, Letterboxd, Whiteboard Journal and other reputable organisations, Bintang leverages their broad range of experiences to resources that educate audiences, build trust, and support business growth.
Aspire Launchpad
Supercharge your finance operations with Aspire
Find out how Aspire can help you speed up your end-to-end finance processes from payments to expense management.

Latest articles
Business Account •
Best real estate accounting software in the US for investors, developers and property managers
Compare real estate accounting software in the US for investors, property managers and developers, with features, pricing, expert assessments and use cases.
Business Account •
Construction company accounting 101: What it is, WIP & revenue
Construction accounting guide for contractors: 3 decisions to protect profit and cash flow. Learn job costing, revenue recognition, and WIP reporting.
Expense Management •
SaaS spend management: How to control software costs and subscription spend
A complete guide to SaaS spend management, common challenges, cost-saving strategies, and an ideal way to centralize subscription tracking.