
Top 5 Corporate Cards for Agencies in HK
Galih Gumelar

Summary
Funding model: Whether a card spends from a client-funded balance or from the agency's own credit matters more to an agency than any rewards rate.
Cash flow: Fronting client ad spend ties up the agency's cash, and the exposure grows with every client added.
Margin: Agencies that bill ad spend back to clients need exact per-client spend, and manual reconciliation puts that margin at risk.
Currency: Paying a foreign currency by card usually adds a handling fee of about 0% to 2.5%, according to the HKMA.¹
Comparison basis: The cards are our Multi-Currency Card, our Advanced Card, the HSBC Business Mastercard, the American Express Gold Business Card and the Cathay Pacific Elite Corporate Card.
Say an agency runs Facebook ads for a client and spends HKD 50,000 this month. There are 2 ways that money can move. Either the client's funds sit in the account paying for the ads directly, or the agency puts HKD 50,000 on its own card first, invoices the client and waits to be paid back.
Most corporate card comparisons never ask which of these 2 models a card supports. They compare rewards rates and lounge access instead, which is the wrong question for an agency running ad spend across dozens of clients.
How do the 5 cards compare for agencies?
The cards differ most in who funds the spend and in how they reward overseas and online charges. The table uses each issuer's published terms where they exist, and the figures can change.
| Card | Funding model | Rewards | Credit terms |
|---|---|---|---|
| Aspire Multi-Currency Card | Spends from the account balance, 13 currencies | 1.2% cashback on eligible spend | No credit line |
| Aspire Advanced Card | Credit-based, for eligible businesses | 1.2% cashback on eligible spend | Up to 51 days interest-free |
| HSBC Business Mastercard | Credit card² | 1 RewardCash per HKD 250, or 2 per HKD 250 overseas and online on the World card | Up to 56 days interest-free |
| American Express Gold Business Card | Charge card, no pre-set limit³ | Up to 3 Membership Rewards points per HKD 1 of foreign currency spend | Up to 51 credit-free days, HKD 980 annual fee with the first year waived |
| Cathay Pacific Elite Corporate Card | Charge card | 1 Asia Mile per HKD 7⁴ | Not stated |
The bank card pages reviewed do not describe issuing 1 card per client. Confirm that and the foreign currency fee with each issuer before you apply.
For the wider market, see our guides to the corporate credit card and cashback cards for Hong Kong businesses.
What are the real pain points?
The funding question is the source of most of the problems agencies run into with ad spend cards. The sections below take 4 of them in turn.
How does fronting hurt cash flow?
An agency that fronts client ad spend carries that cash until the client pays. With 20 clients each spending HKD 50,000 a month, the agency has HKD 1,000,000 tied up every month before invoices are settled.
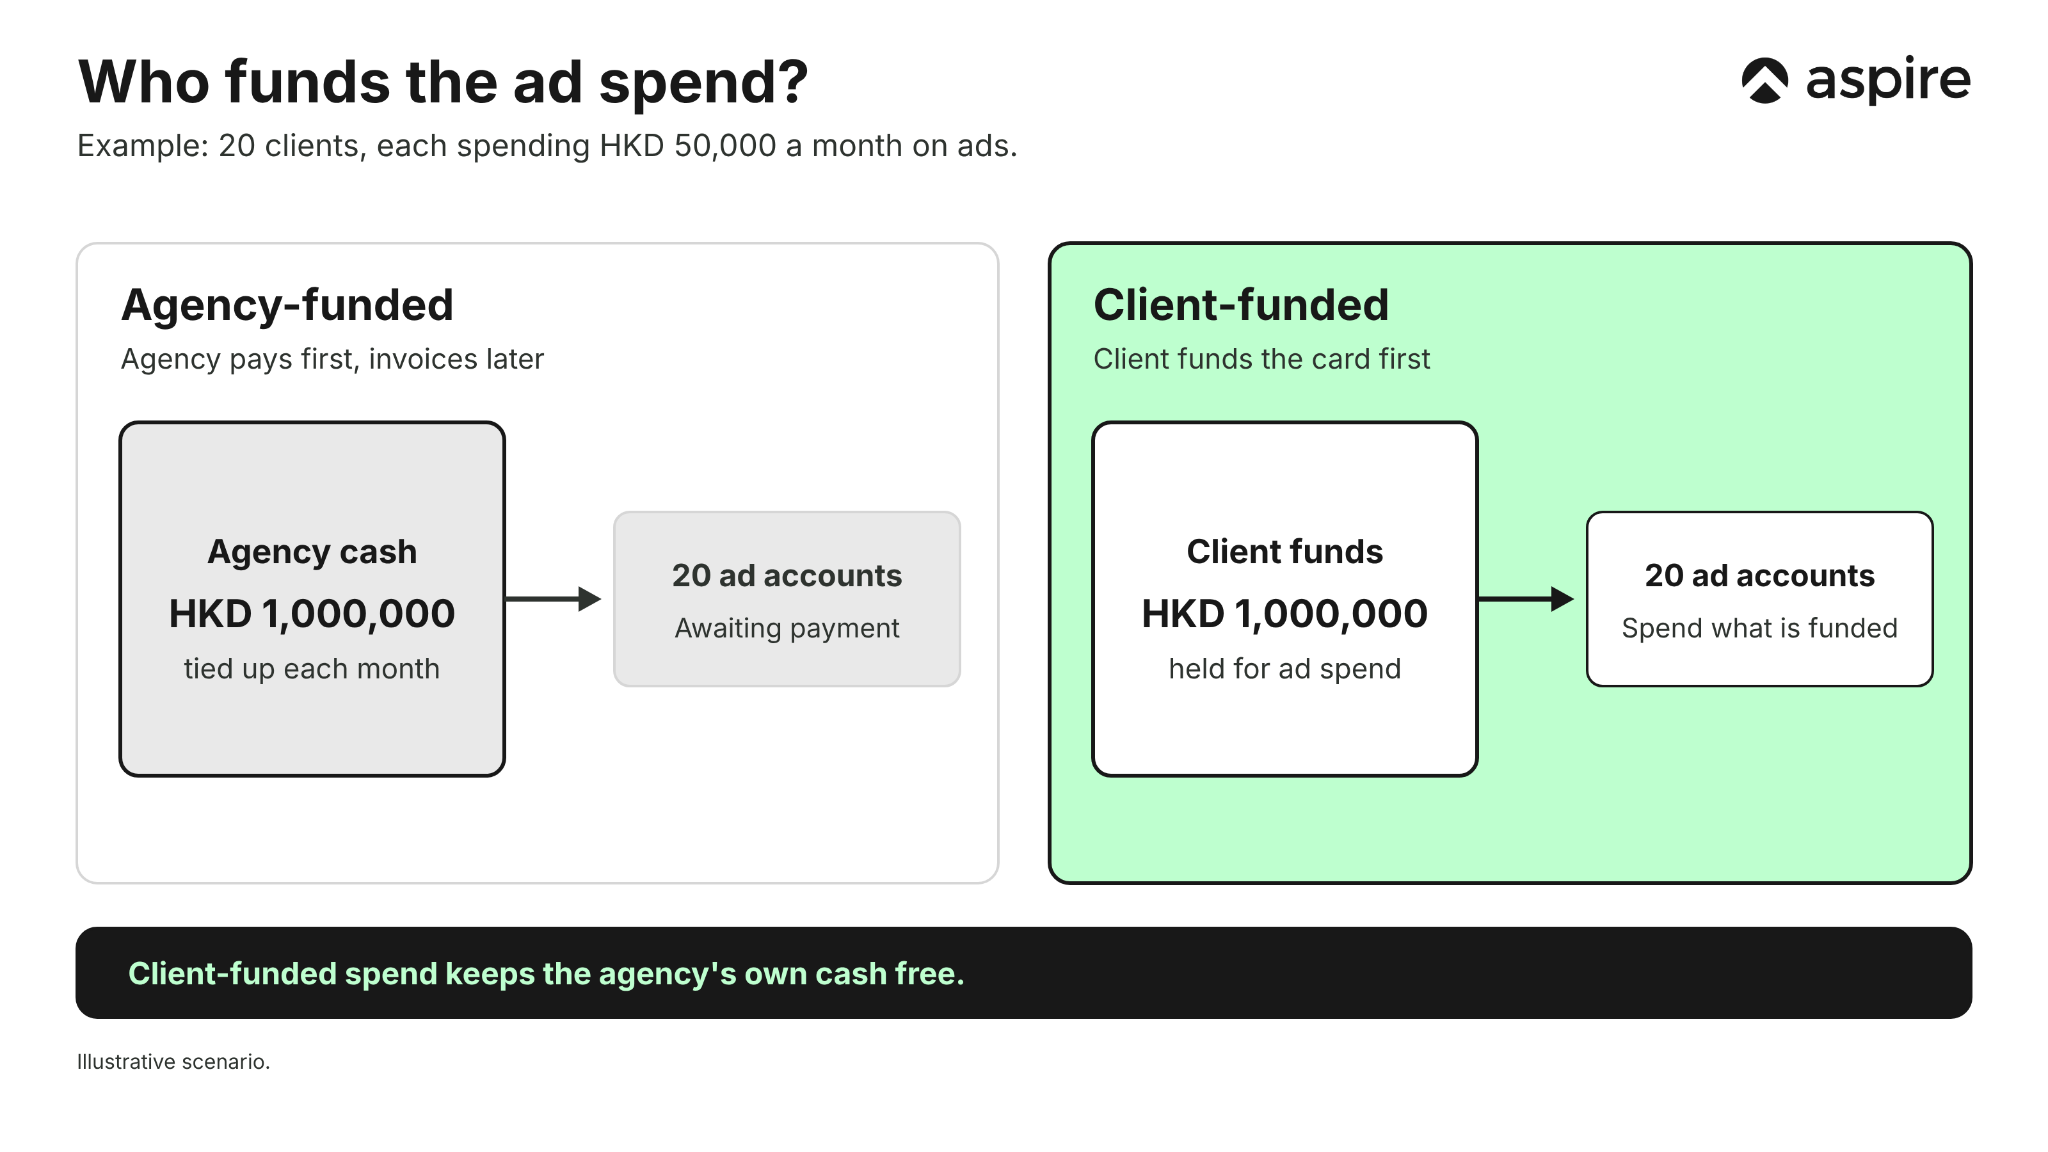
A single late-paying client creates a gap the agency covers out of pocket. This strain exists even when the agency is profitable on paper, because the cash is simply not available when it is needed.
How does it create margin risk?
Agencies that mark up media spend or bundle it into a management fee need exact spend per client. Manual reconciliation across many clients and platforms leaves room for billing errors.
An error that undercharges a client comes straight out of agency margin, not just administrative time. Spend that is attributable at the point of transaction removes the guesswork before it becomes a margin problem.
What do foreign currency ad bills cost?
Ad platforms often bill in a currency that is not HKD, and a card converts each charge at the point of sale. The HKMA says paying in a foreign currency usually triggers a handling fee of about 0% to 2.5% from the card issuer, on top of the exchange rate.¹
The Consumer Council found the highest fee among the cards it surveyed in 2015 was 2.45%.⁵ Both figures date from 2015, so check current fee schedules in each card agreement.
How do you segregate spend by client?
A shared card makes it hard to answer how much was spent on 1 client's ads this month. Answering means manual sorting across platforms and statements.
With 1 virtual card per client, that answer already sits in the transaction data. See our guides to virtual cards in Hong Kong and virtual cards vs physical cards.
What actually solves each pain point?
The pattern is to build the card setup around client and campaign separation from the start. Sorting it out after the fact costs more.
| Pain point | What solves it |
|---|---|
| Fronting client cash before invoicing | Client funds held in the account, with a balance-funded card that spends only what is available |
| Margin erosion from reconciliation errors | 1 virtual card per client, so spend is attributable at the point of transaction |
| Foreign currency fees on ad bills | A multi-currency account that holds and pays in the billing currency |
| Spend mixed across clients | Spend limits per card, plus 1 virtual card per client or campaign |
What does this look like in practice?
The fixes play out differently for each type of agency. 3 scenarios show the pattern, and all 3 are invented for illustration.
How does a performance agency run 20 clients?
An agency running Facebook, Google and TikTok campaigns for 20 clients can issue 1 virtual card per client. If each client prefunds its own budget, each card spends only what has been funded, and the agency does not carry the gap.
Say the agency's clients spend HKD 1,000,000 a month in total. At 1.2% cashback that is HKD 12,000 a month, compared with HKD 4,000 at the HSBC card's published base rate and HKD 8,000 at the World card's overseas and online rate.
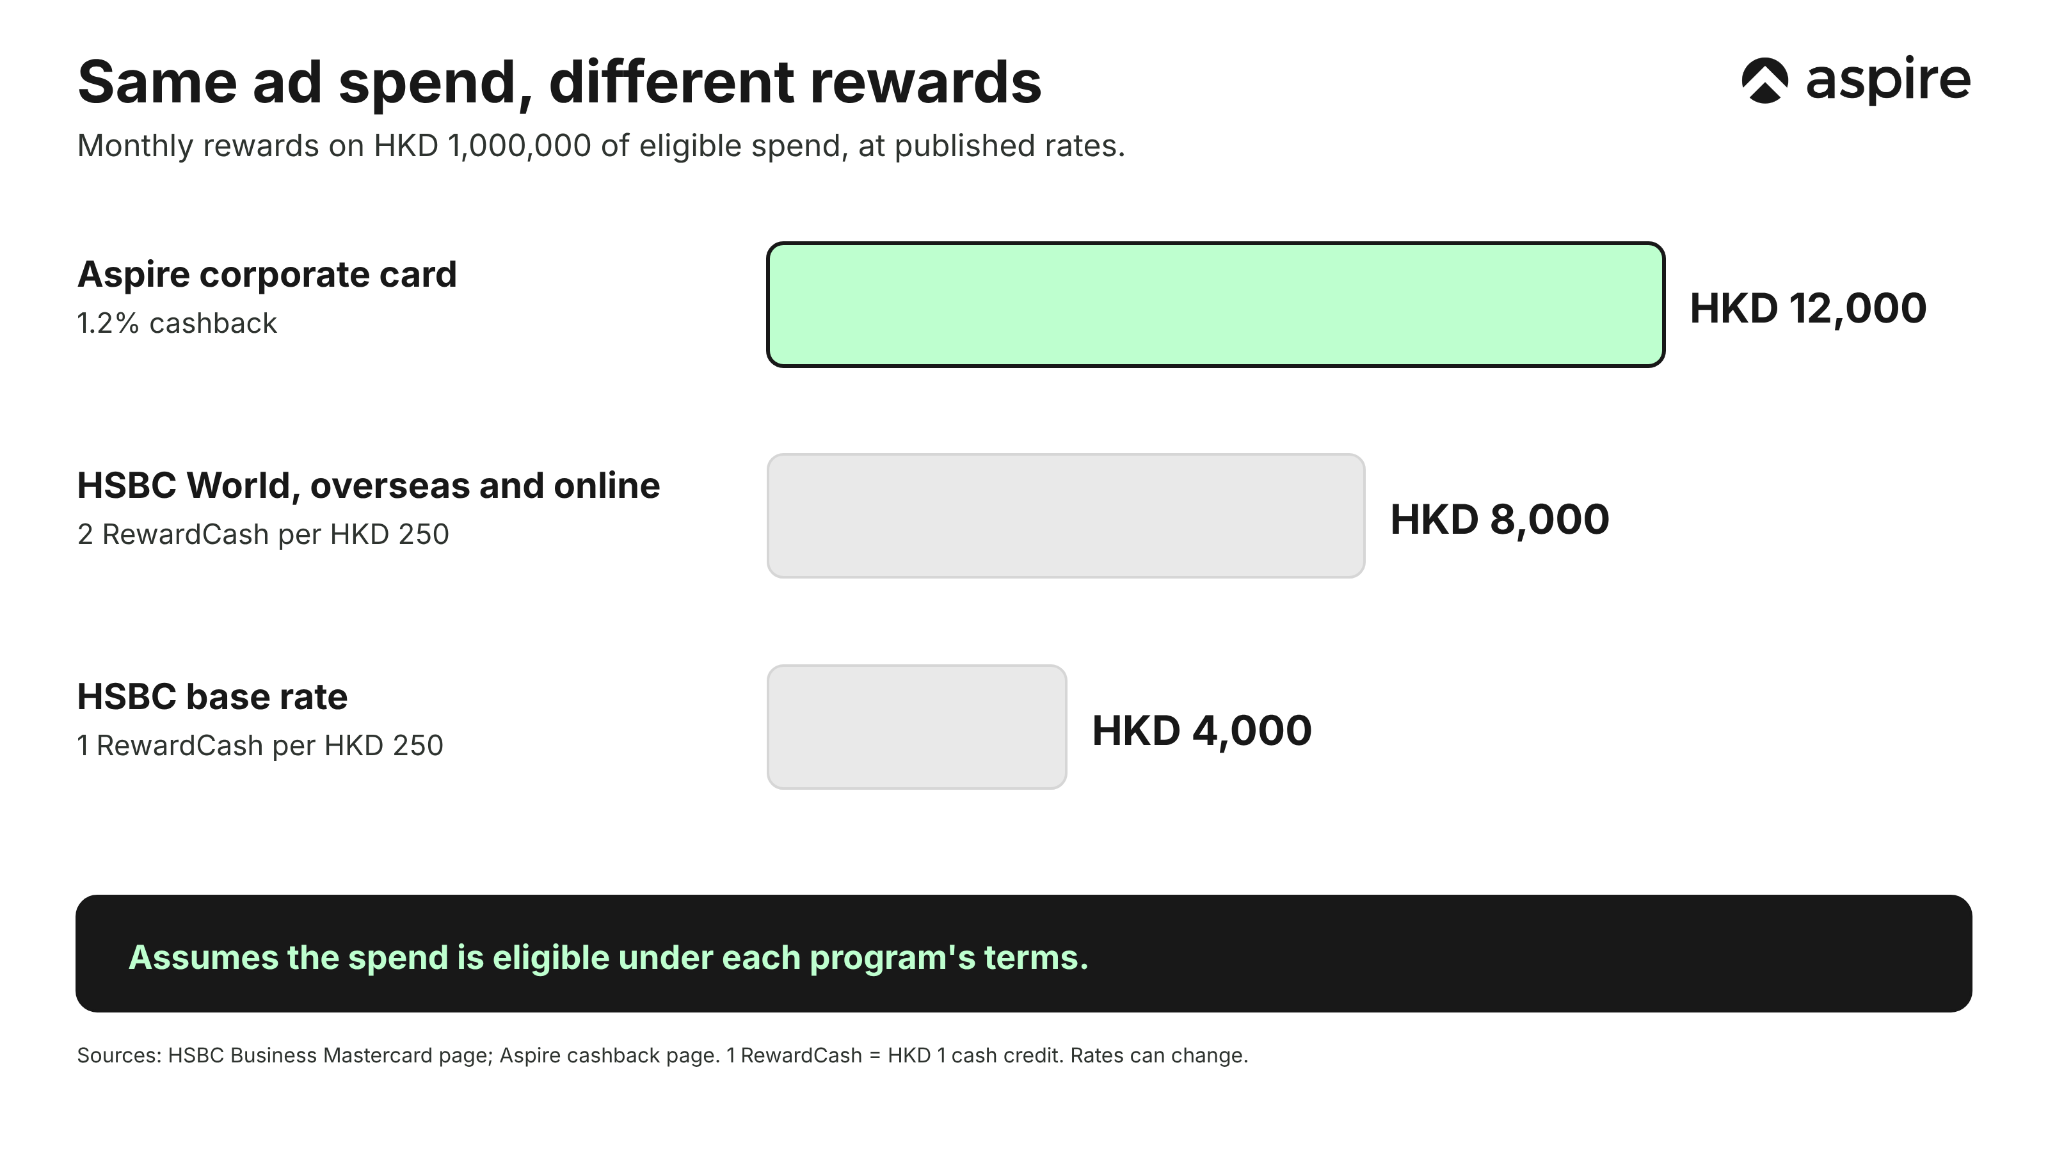
The comparison assumes the spend is eligible under each program. Our cashback page lists digital marketing among eligible spend, so check the cashback policy for exclusions.
How does a creative agency bill in several currencies?
A creative agency with Hong Kong and overseas clients can hold the currency each client pays in. It can then pay overseas contractors and USD-billed software from that balance, instead of converting twice.
Holding USD or EUR avoids converting at the point of each foreign payment, and spending in USD or HKD avoids FX fees on our card. See our guides to foreign currency accounts and cross-border payments.
How does a growing agency separate its own spend?
An agency can keep client campaign spend and its own operating spend on different cards. Client budgets sit on balance-funded cards, while the agency's own software and overheads sit on a credit line if it wants one.
Mixing the 2 is the pattern that recreates the fronting and margin risk described above. See our guide to expense management.
When does a rewards card make sense?
A points or miles card suits an agency with modest, steady ad volume and mostly its own overheads. The points earned then outweigh the manual work of tracking spend by client.
It makes less sense as client count grows, because the funding risk and reconciliation burden compound. For a different spend profile, see our guide to corporate cards for travel.
How does Aspire support agencies?
We build agency spend around funding structure and client separation, not rewards categories.
- Balance-funded card. Our Multi-Currency Card spends from the account balance and works in 13 currencies.
- Optional credit. Our Advanced Card offers a credit line for eligible businesses, and our corporate card page describes an optional credit line in HKD or USD subject to approval.
- Per-client virtual cards. You can issue multiple virtual cards at no extra cost, and each supports spend limits and budgets.
- Flat cashback. You earn 1.2% on eligible spend, with terms in our cashback policy.
See the corporate card page for current terms, and Zenyum's case study for a time saving reported at company scale.
Why Hong Kong Businesses Choose Aspire
Managing ad spend across dozens of clients is 1 part of running an efficient agency, and Aspire is built to support the funding and reconciliation work around all of it.
💱 FX spreads from 0.18%, up to 3x cheaper than traditional banks. This applies across 130+ countries and 40+ currencies through Aspire's multi-currency account. It's useful for anything from paying overseas contractors to settling international payments without losing margin to markup.
💰 1.2% unlimited cashback applies on every corporate card transaction, with no monthly cap. It kicks in automatically on eligible spend, with no minimum threshold to hit first. Over time, it quietly turns routine business spend into working capital.
🌐 Local transfer network, not multi-hop SWIFT chains, is how Aspire routes most payments. This means faster settlement and fewer intermediary fees eating into your payment before it reaches the recipient. It also reduces the chance of funds being held up for review at a correspondent bank along the way.
💸 Fixed USD 8 inbound SWIFT fee, tracked end-to-end with SWIFT GPI, applies when SWIFT is the right rail for your payment. There are no surprise deductions from correspondent banks along the way, so the amount you're quoted is the amount that arrives. You can also download payment confirmation instantly from the app, without calling the bank.
⚡ Approved in as little as 1 business day, with no branch visits and no paperwork stacks. Applications are completed entirely online, from document upload to approval. There's no waiting weeks on a relationship manager to call you back.
Open a free multi-currency business account built for Hong Kong SMEs, or explore how Aspire's corporate card fits into your agency's day-to-day ad spend.
Frequently Asked Questions
In a client-funded model, the client's money sits in the account paying for ads, so the agency spends none of its own cash. In an agency-funded model, the agency pays first on its own card, then invoices and waits for reimbursement.
The gap between paying the platform and receiving payment is covered by the agency's own cash. Across many clients, or with 1 late payer, that creates strain even when the agency is profitable.
It makes spend attributable to the right client at the point of transaction. Billing errors from manual reconciliation then stop coming out of profit.
It depends on the disruption against the ongoing benefit. Timing the change at a billing cycle boundary is usually easier than switching mid-campaign.
Sources
- HKMA, "Hong Kong Dollars or Foreign Currencies? Making the Smart Choice when Using your Credit Cards Overseas" (December 2015)
- HSBC Hong Kong, "Business Mastercard" product page (issuer terms, accessed November 2026)
- American Express Hong Kong, "Gold Business Card" product page (issuer terms, accessed November 2026)
- American Express Hong Kong, "Business and Corporate Cards" (issuer terms, accessed November 2026)
- Consumer Council, "Credit card transaction fees" (press release, 15 December 2015)
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our 'Terms of Service' and 'Pricing' pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Galih Gumelar
Writer
Galih is a seasoned writer specialising in macroeconomics, business, finance and politics. With a writing history at CNN Indonesia, The Jakarta Post, and various other reputed organisations, Galih leverages his broad range of experiences to create insightful resources for those wanting to start a business.
Aspire Launchpad
Start Your Business with Aspire Launchpad
From incorporation to venture capital, we connect you with trusted service providers to make your entrpreneurial journey seamless.
Latest articles
Corporate Card •
Top 4 Business Cards for Freelancers in HK
Compare 4 business cards for HK freelancers and sole proprietors. See eligibility, personal liability, irregular income and multi-currency controls.
Corporate Card •
Top 4 Corporate Cards for E-commerce in HK
Compare 4 corporate cards for HK e-commerce on rewards and credit terms, and see how virtual cards and multi-currency tools help ad and inventory spend.
Corporate Card •
Top 5 Travel Corporate Cards for HK Companies
Compare 5 corporate cards for travel in HK on rewards, fees and perks, and see how virtual cards and multi-currency tools cut FX cost.
Start your journey with Aspire
Open your free account