What Is a Letter of Credit?
A Letter of Credit is a formal written undertaking by a bank, on behalf of a buyer (the applicant), to pay a seller (the beneficiary) a specified sum, provided the seller presents documents that comply strictly with the LC's terms. It's also known as a documentary credit, and it's widely used in international trade.
The core function is substituting the bank's creditworthiness for the buyer's. This matters most where a seller has limited visibility into a buyer's financial stability, since the issuing bank effectively assumes the buyer's credit risk.
This gives the seller unparalleled payment security, provided they ship the goods and present the correct paperwork.
LCs are governed by the Uniform Customs and Practice for Documentary Credits (UCP 600), published by the International Chamber of Commerce.
The credit agreement between bank and applicant is separate from the underlying sales contract, creating a clear framework for dispute resolution.
Who Are the Key Parties in a Letter of Credit?
Up to 5 distinct parties can be involved in a single LC transaction, each with a specific role:
How Does the Letter of Credit Process Actually Work?
The fundamental steps stay consistent across most transactions, even as specific details vary:
- Sales agreement: buyer and seller agree on price, quantity, shipping, and stipulate payment via LC in the contract
- LC application: the buyer applies to their bank, specifying required documents, shipment deadlines, and the credit's expiry date
- LC issuance: after assessing creditworthiness, the issuing bank approves and transmits the LC to the advising bank, typically via SWIFT
- Advising the LC: the advising bank authenticates it and forwards it to the seller, who checks it matches the sales contract
- Shipment of goods: the seller ships the goods as specified, confident in the bank's payment guarantee
- Document presentation: the seller submits the required documents (commercial invoice, bill of lading, insurance policy, certificate of origin, packing list) to their bank
- Document examination: the bank checks for a "complying presentation." A sight LC pays immediately; a usance LC accepts a draft payable on a future date
- Interbank settlement: the seller's bank forwards documents to the issuing bank, which reimburses the seller's bank once satisfied
- Final settlement: the issuing bank debits the buyer's account and releases documents, which the buyer uses to claim the goods
What Are the 10 Types of Letters of Credit?
LCs aren't one-size-fits-all — different types have evolved for different trade scenarios:
What Are the Benefits and Costs of Using an LC?
LCs offer real security, but that security comes at a real price.
- High payment security: sellers get bank-backed assurance of payment, virtually eliminating buyer credit risk
- Reduced risk for buyers: payment only releases once the seller proves shipment and provides the specified documents
- Access to financing: sellers can often use an LC as collateral for pre- or post-shipment financing
- Facilitates new relationships: LCs enable trade between parties who don't yet know or trust each other
The costs stack up across several distinct fees:
Beyond fees, the process itself is document-intensive and can be slower than open account or direct payment methods, particularly when errors trigger back-and-forth amendments.
How Do You Apply for a Letter of Credit in Hong Kong?
Hong Kong's banking system is well-equipped to handle LCs, with a standardised process across major institutions:
- Establish a banking relationship: open a business account with a bank offering trade finance, such as HSBC, Standard Chartered, or Bank of China (Hong Kong)
- Secure a trade finance facility: this involves a credit assessment of your financial health and trading history, and may require collateral
- Complete the application form: through the bank's trade portal or a physical form
- Provide detailed information: beneficiary details, LC amount and currency, shipment and expiry dates, goods description, Incoterms, and the specific documents required
- Submit and await issuance: the bank's trade finance team reviews for completeness before issuing the LC and transmitting it via SWIFT
What Are the Most Common Letter of Credit Mistakes?
The strict compliance nature of LCs means even minor errors cause real problems:
- Documentary discrepancies: the number 1 cause of payment delays, from typos to inconsistent goods descriptions across documents
- Expired credit or late shipment: missing the presentation deadline or the LC's specified shipment date
- Unworkable terms: a buyer requesting a document type the seller genuinely cannot obtain
- Failing to amend: agreeing to a change verbally but not formally updating the LC, so the original terms still apply
- Incomplete presentation: missing even 1 required document can delay or void payment entirely
What Are the Best Practices for Using a Letter of Credit?
For the seller: review the draft LC before formal issuance, check for ambiguous terms a bank document checker might interpret differently, prepare documents with a checklist and a second reviewer, and track every deadline closely.
For the buyer: be precise without requesting unnecessary documents that complicate the seller's task, set realistic shipping timelines, and communicate openly, especially when amendments become necessary.
When Does a Multi-Currency Account Make More Sense Than an LC?
Letters of Credit remain the gold standard for securing high-value, high-risk shipments, but their procedural complexity and cost can be genuine friction for routine international payments.
For operational payments, supplier settlements, and recurring transactions that don't carry the same risk profile as a one-off high-value shipment, a full LC process is often more than the situation calls for.
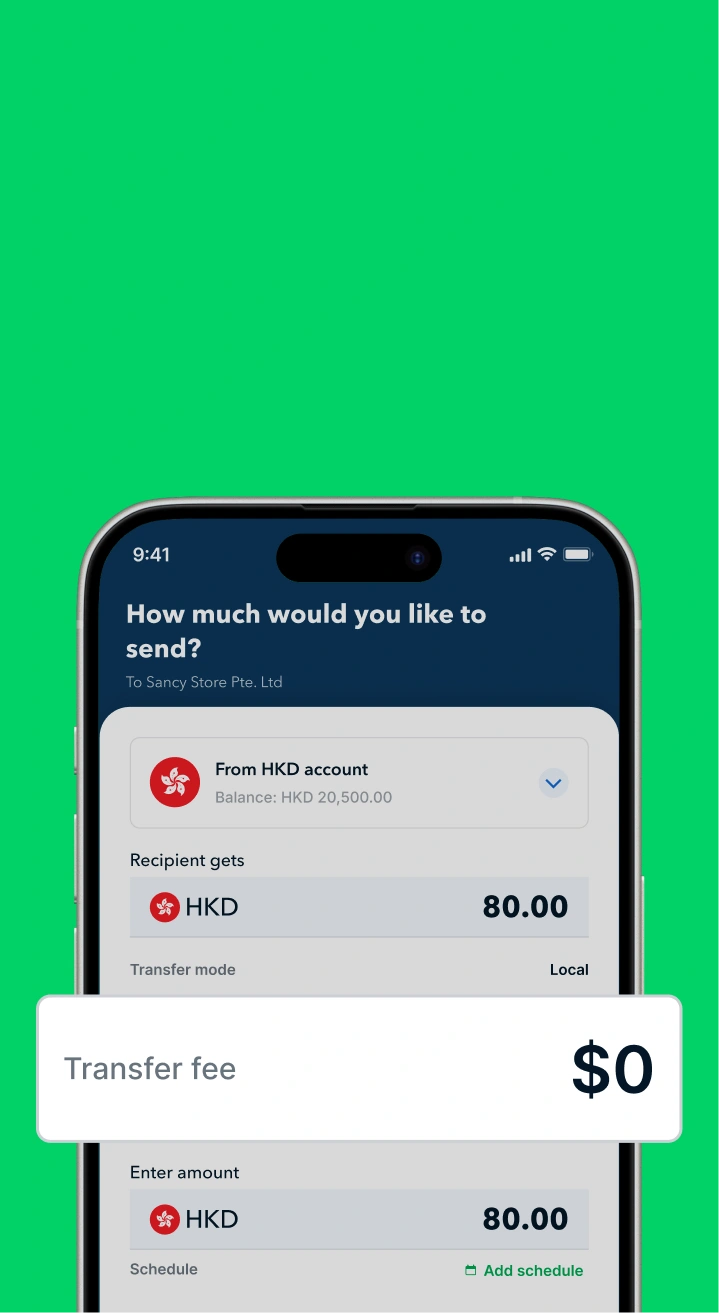
Aspire's multi-currency account lets a business hold, send, and receive funds across 130+ countries and 30+ currencies, reducing conversion costs and FX risk without the paperwork overhead an LC requires.
Combined with faster international transfers and integrated expense management, this handles day-to-day payments to suppliers, contractors, and partners with far more speed than a documentary credit process allows.
A sensible hybrid approach reserves LCs for genuinely large, high-risk shipments where their security is worth the cost, while routing recurring and operational international payments through a faster, lower-friction platform instead.
Why Hong Kong Businesses Choose Aspire
Trade finance instruments like LCs protect your biggest shipments — Aspire is built to make everything else about international payments fast and simple.
💱 FX spreads from 0.18%, up to 3x cheaper than traditional banks. This applies across 130+ countries and 40+ currencies through Aspire's multi-currency account. It's useful for anything from paying overseas suppliers to settling international payments without losing margin to markup.
💰 1.2% unlimited cashback applies on every corporate card transaction, with no monthly cap. It kicks in automatically on eligible spend, with no minimum threshold to hit first.
🌐 Local transfer network, not multi-hop SWIFT chains, is how Aspire routes most payments. This means faster settlement and fewer intermediary fees eating into your payment before it reaches the recipient.
💸 Fixed USD 8 inbound SWIFT fee, tracked end-to-end with SWIFT GPI, applies when SWIFT is the right rail for your payment. There are no surprise deductions from correspondent banks along the way.
⚡ Approved in as little as 1 business day, with no branch visits and no paperwork stacks. Applications are completed entirely online, from document upload to approval.
Open a free multi-currency business account built for Hong Kong SMEs, or explore how Aspire's corporate card fits into your day-to-day spend.
Frequently Asked Questions
What's the difference between a sight LC and a usance LC?
A sight LC pays the seller immediately, typically within 5-10 banking days of compliant documents being presented. A usance LC delays payment to a specified future date after document acceptance, effectively giving the buyer short-term financing.
Why do documentary discrepancies cause so many problems?
Because LCs operate on strict compliance: banks pay based on documents matching the LC's terms exactly, not on whether the underlying trade was conducted in good faith. Even a typo or inconsistent goods description across documents can delay or block payment entirely.
Is a Standby LC the same as a Commercial LC?
No. A Commercial LC is the primary payment method for a specific shipment. A Standby LC is a secondary safety net, functioning like a bank guarantee that's only drawn on if the applicant fails to meet their obligations.
Do I need an LC for every international transaction?
Not necessarily. LCs make the most sense for high-value or higher-risk shipments, particularly with new trading partners. For recurring, lower-risk international payments, a multi-currency account can handle the transaction faster and with less overhead.
How much does a Letter of Credit typically cost?
Costs vary by bank and LC type, but issuance fees commonly run 0.5%-2% of the LC's value, charged to the buyer. Additional fees apply for confirmation, advising, discrepancies, and amendments, so the total cost depends heavily on how smoothly the transaction proceeds.