

Top 6 Fintech Global Payment Solutions for HK Businesses
Galih Gumelar

Summary
Global payments do 3 jobs. They send money to suppliers, receive money from overseas clients and collect card payments from foreign customers.
Fees sit in 3 places. Transfer fees, FX markups and receiving or withdrawal fees each hit a different step.
Stated rates vary widely. PayPal states 4.40% + HKD 2.35 for cross-border payments, while Stripe states 3.4% + HKD 2.35 plus 0.5% for international cards.¹ ²
Local rails skip SWIFT. Our same-day transfers cover 40+ currencies.
The better choice depends on the job. Banks charge fixed fees per wire, while fintech accounts can offer free local transfers.
"Not stated" is common. Several providers publish no transfer FX markup, so compare the full cost on a real payment.
Global payment solutions are the accounts, platforms and bank services a business uses to send, receive and collect money across borders. A Hong Kong importer paying a supplier in USD and an online brand selling to overseas shoppers both need them.
This guide compares 6 top fintech solutions by what each states about fees, coverage and speed. It then explains how banks differ, shows 3 example banks and covers how to choose.
What are global payment solutions?
Global payment solutions are services that move money between countries and currencies. They cover transfers, multi-currency accounts, payment gateways and bank wires.
Our guide to cross-border payments explains the mechanics step by step. This guide focuses on comparing providers.
Which types of global payment exist?
Hong Kong businesses use global payments for 3 jobs: sending, receiving and collecting. The table maps each job to its tools and to our deeper guide.
| Job | Typical tools | Read more |
|---|---|---|
| Send | Multi-currency accounts, bank wires, local payouts | International payments |
| Receive | Local account details, inbound SWIFT, marketplace payouts | B2B payment methods |
| Collect | Payment gateways, wallets, card acceptance | Digital payment solutions |
We cover sending and receiving from 1 account. Our global payments reach 130+ countries in 40+ currencies.
Which are the top global payment solutions?
These 6 fintech solutions state different fees and coverage, and we list ours first. The table shows what each states, and rates change, so check current terms.
| Solution | Fees and terms stated | What to know |
|---|---|---|
| Aspire | International payments to 130+ countries in 40+ currencies, same-day transfers, no account opening or monthly maintenance fees, free local transfers in major currencies | Limits and cut-off times are not stated |
| Airwallex | 2.00% FX conversion fee and 1.00% foreign currency settlement fee on payment acceptance³ ⁴ | Transfer FX markup, SWIFT and receiving fees are not stated⁴ |
| Wise Business | HKD 199 one-time fee for local account details in 22 currencies; free local receiving in 9 currencies; SWIFT receiving at USD 6.11, GBP 2.16 or EUR 2.39⁵ | Sending fee is not stated on the receiving page⁵ |
| Payoneer | HKD 12 to withdraw HKD to a Hong Kong bank; up to 3% for non-local currency withdrawals; USD 29.95 annual fee with waivers⁶ | Receiving fee is not stated⁶ |
| PayPal | 4.40% + HKD 2.35 for standard cross-border payments; 3.00% above base rate to convert received payments¹ | Other currency conversions cost 4.00% above the base rate¹ |
| Stripe | 3.4% + HKD 2.35 domestic cards; +0.5% international cards; +2% if conversion is needed² | Collects card payments through a gateway connected to our account |
Our international payments run on Wise Platform and are live for all Hong Kong customers. Our Wise partnership announcement covers the launch.
To receive money, you get local account details in HKD, CNY, USD, EUR and GBP with us.
How do fintechs differ from banks?
A bank is an institution licensed by the HKMA to take deposits, while a fintech is a technology-led provider that offers a narrower service. The HKMA licenses banking and deposit-taking businesses in 3 tiers: licensed banks, restricted licence banks and deposit-taking companies.⁷
Licensed banks take deposits of any size from the public and run current and savings accounts.⁷ A fintech usually focuses on 1 job, such as transfers, multi-currency accounts or payment acceptance.
Which is better: a fintech or a bank?
Neither wins on every payment; the better choice depends on how often you pay abroad and in which currencies. A bank suits a business that sends a few wires a year and already holds its operating account there.
A fintech account suits frequent payments in several currencies. A business sending 20 supplier payments a month pays HKD 2,500 in HSBC's stated online TT fees before overseas bank charges.⁸ The same 20 payments cost nothing in transfer fees through our local transfers in major currencies, where a local route exists.
Which banks offer global payments?
Traditional banks send money abroad through telegraphic transfers (TT), usually at fixed fees per payment. Many more banks operate in Hong Kong, so the table shows 3 examples and what each states.
| Bank | Fees and terms stated | What to know |
|---|---|---|
| HSBC | Outward TT HKD 125 online to most destinations, HKD 100 to HSBC offices in Mainland China, HKD 480 at a branch; inward TT HKD 65⁸ | Overseas bank charges are extra⁸ |
| Hang Seng Bank | Outward TT HKD 125 online to other banks and countries, HKD 85 to Hang Seng in Mainland China or Macau, from HKD 300 at a branch; inward TT HKD 65⁹ | Online transfers to other countries also incur correspondent bank charges⁹ |
| DBS Hong Kong | TT in 39 currencies; outward cut-off 5:30pm on business days for HKD, USD, GBP and EUR through DBS IDEAL¹⁰ | Fee amounts sit in its Bank Charges Schedule and are not stated on the page¹⁰ |
A Hong Kong importer can keep its main account at a bank and send supplier payments through a multi-currency account. The checklist below includes the licence check.
What do global payments cost?
A cross-border payment can lose money at 3 steps: the transfer fee, the FX markup and the receiving fee. Some providers bundle these, while others show each one.
The diagram works through USD 10,000 of overseas card sales, using the rates the providers state.¹ ²
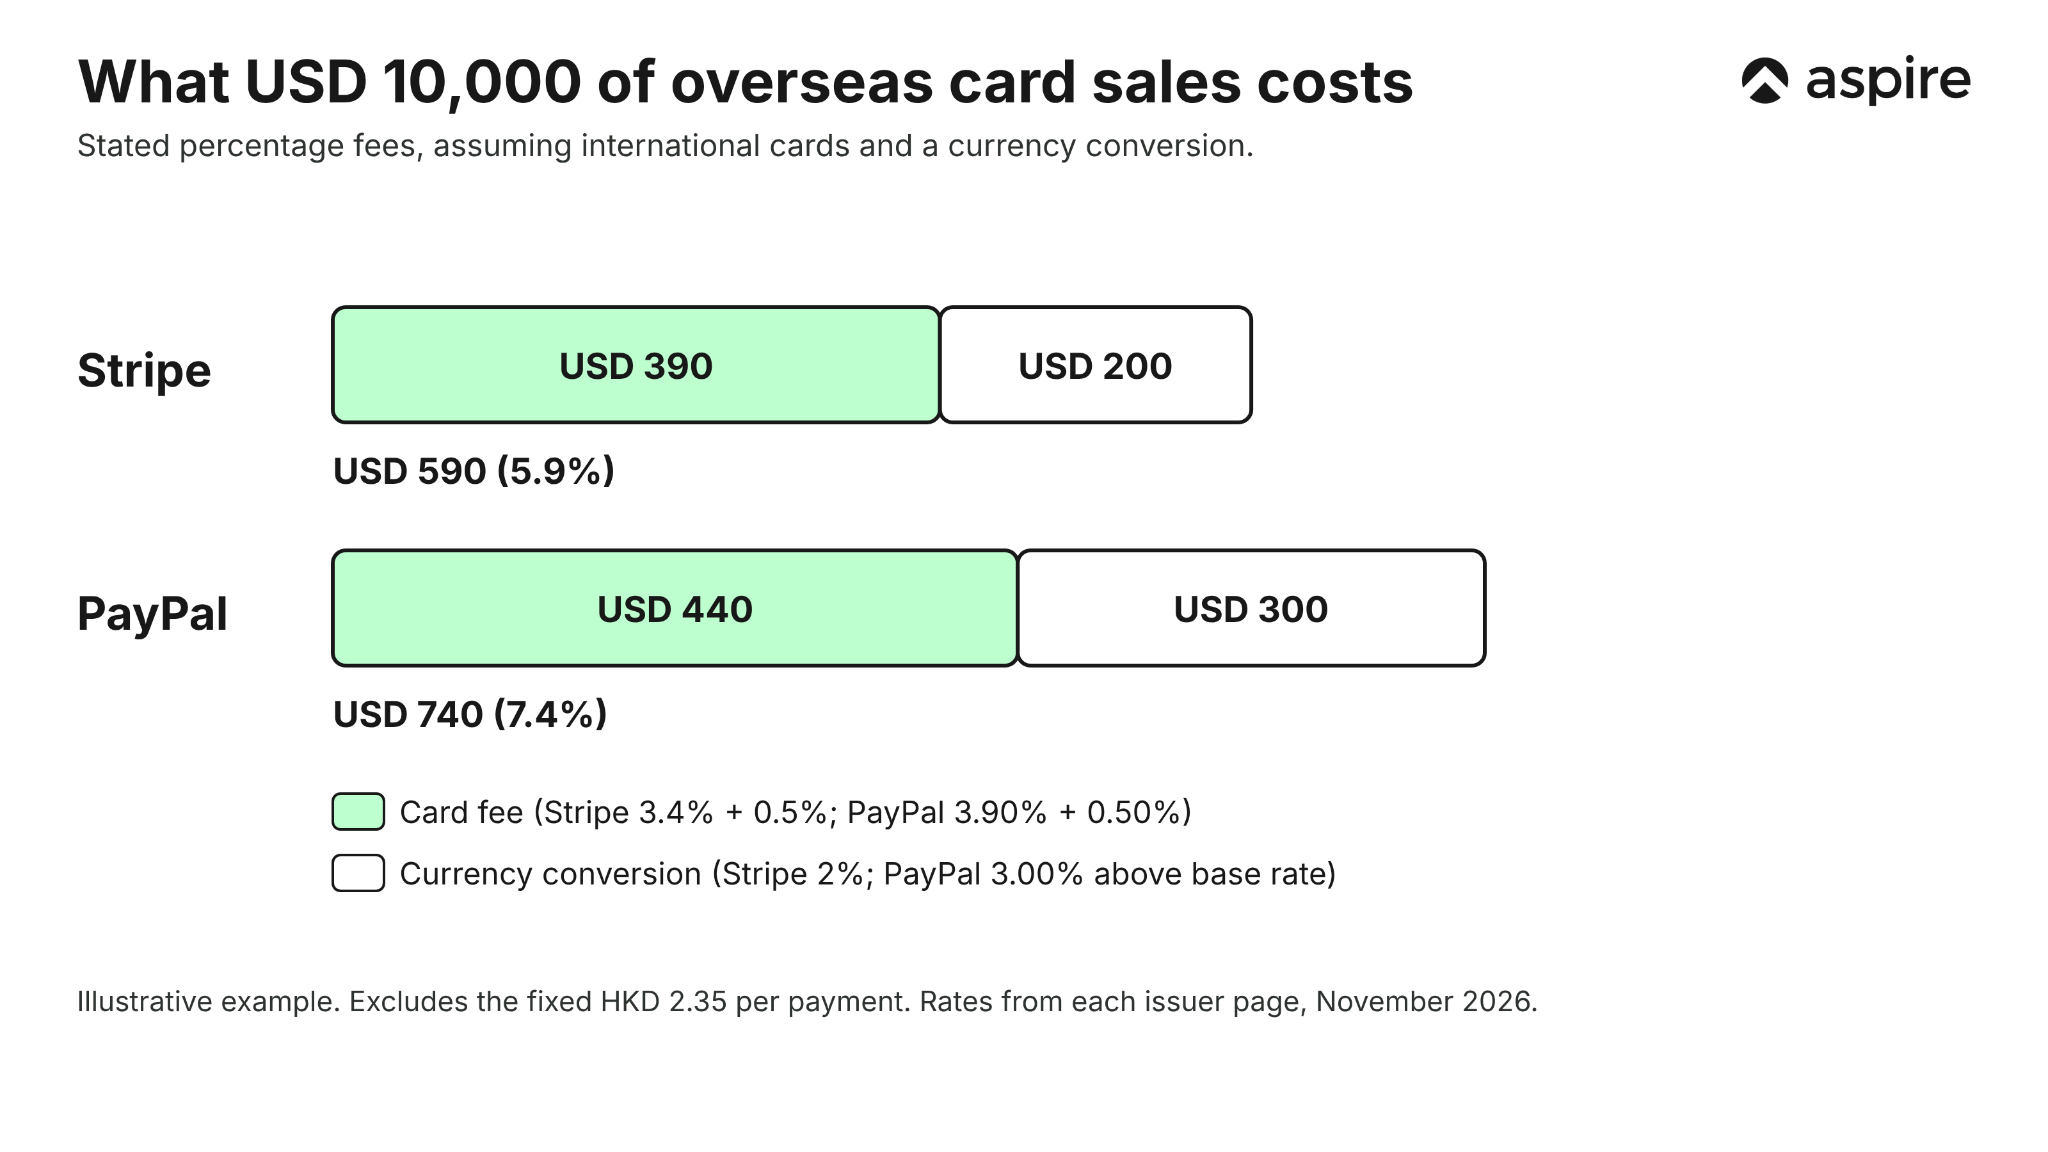
Fixed per-payment fees add up on small orders. Stripe and PayPal each state a fixed HKD 2.35 fee per payment.² ¹ At that rate, 100 orders of USD 100 cost HKD 235 before any percentage.
What does Aspire charge for local and SWIFT?
Our local transfers in major currencies are free, while an inbound SWIFT payment carries a fixed USD 8 fee. The table shows how the routes differ.
| Route | Our rate | What to know |
|---|---|---|
| Local transfer | Free in major currencies | Same-day transfers are available in 40+ currencies |
| Inbound SWIFT | Fixed USD 8 fee | The fee stays the same whatever the payment amount, and SWIFT GPI tracks the payment |
| Currency conversion | FX spreads from 0.18% | Applies only when a payment needs a conversion |
Routing a payment locally avoids the SWIFT fee altogether. Use SWIFT when the recipient's country or bank has no local route.
How fast are global payments?
Local payouts typically settle the same day or within 1 business day, while SWIFT payments typically take 1 to 5 business days. The gap comes from where the money has to travel.
A SWIFT payment crosses borders through correspondent banks, and each hop adds handling time and possible fees.
A local payout does not move your money across borders payment by payment. When you pay from your Hong Kong account, we pay the recipient from our own account in their country, over the domestic network. We settle between our accounts separately, so the recipient sees an ordinary local transfer, though the exact setup varies by corridor.
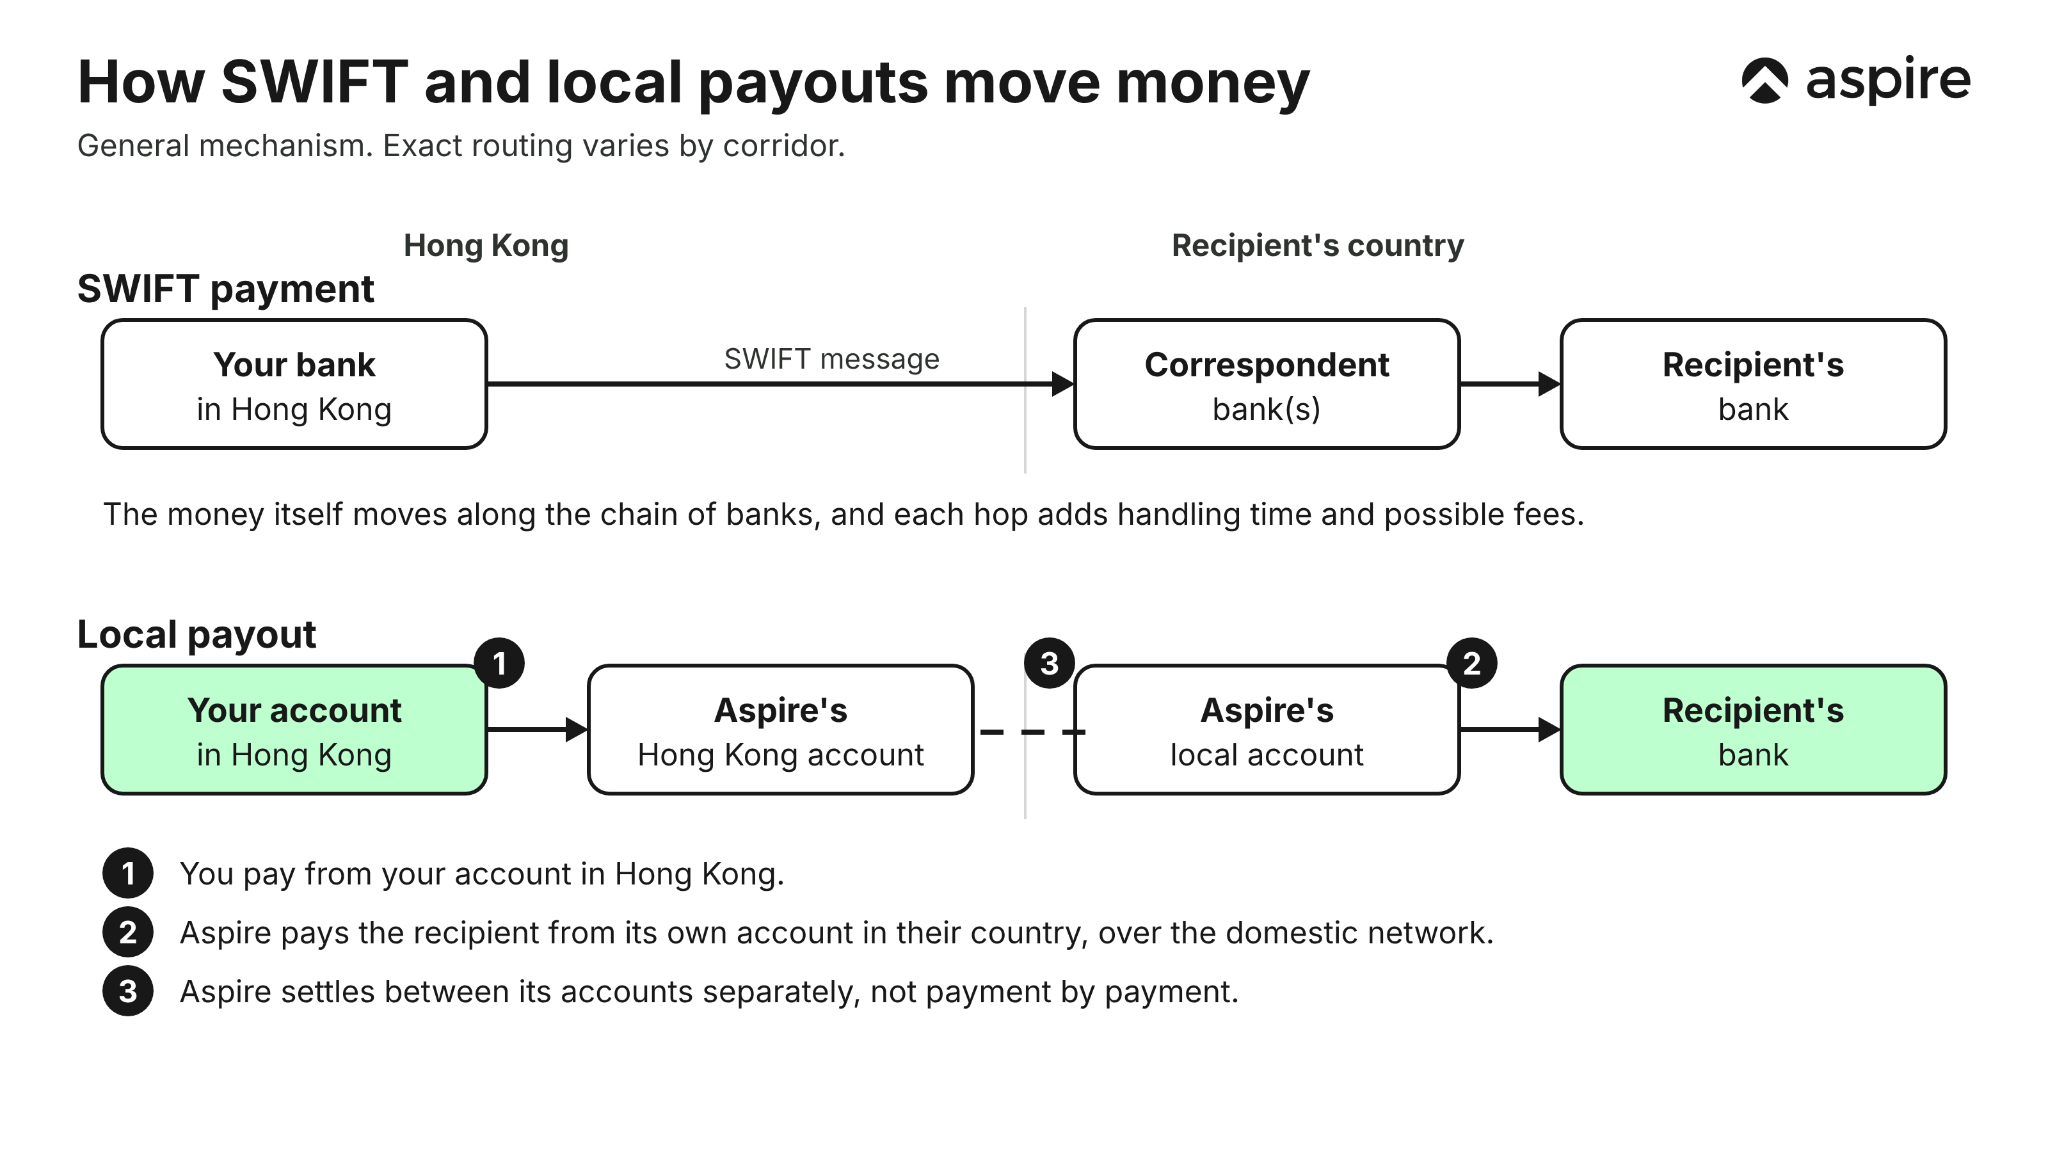
Our guide to SWIFT payments explains the steps, and SWIFT GPI adds tracking.
We offer same-day transfers in 40+ currencies, so many payments skip the multi-day SWIFT wait.
How do you cut cross-border costs?
You cut costs by avoiding repeated conversions and unnecessary SWIFT hops. These 5 habits apply to any provider.
- Match currencies. Invoice in a currency you already hold, so you convert less often.
- Use local rails. Pay in the destination currency through a local payout when the route supports it.
- Batch payments. Group supplier payments, so fixed per-payment fees apply less often.
- Ask for an all-in quote. Compare what the recipient receives, not the headline fee.
- Keep balances. Hold incoming foreign currency until you need to pay in it.
Our business account supports these habits. You can hold balances in 13 currencies and convert only when you need to.
How do you choose a provider?
Choose on the job, the all-in cost, the speed and the controls. Use this 7-point checklist.
A Hong Kong home-goods importer paying a Shenzhen supplier in CNY and a US freelancer in USD needs sending tools. With us, that importer can pay both from 1 account, or upload 1 file through our bulk payments. An online brand selling to overseas shoppers needs collection tools first.
- Job. Decide whether you send, receive or collect.
- All-in cost. Price a real payment, including the FX markup and any receiving fee.
- Coverage. Check the countries and currencies you pay or receive in.
- Speed. Ask whether your routes use local rails or SWIFT.
- Accounting. Confirm that payments sync to your books.
- Controls. Look for approvals and user permissions.
- Licence. Confirm which regulator licenses the provider, and for which services.
What risks come with global payments?
The main risks are hidden fees, failed payments and payee errors. Check these 4 points.
- Fee gaps. Ask for the full fee schedule, including conversion and receiving fees.
- Intermediary charges. HSBC states that overseas bank charges are extra, so the recipient may receive less than you sent.⁸
- Payee errors. Verify account names and currencies before every payment.
- Access. Give each user only the permissions they need.
Why Hong Kong Businesses Choose Aspire
Global payments are 1 part of running a cross-border business, and Aspire supports the accounts, cards and transfers that surround them.
💱 FX spreads from 0.18%, up to 3x cheaper than traditional banks. This applies across 130+ countries and 40+ currencies through Aspire's multi-currency account. It's useful for anything from paying overseas suppliers to settling international payments without losing margin to markup.
💰 1.2% unlimited cashback applies on every corporate card transaction, with no monthly cap. It kicks in automatically on eligible spend, with no minimum threshold to hit first. Over time, it quietly turns routine business spend into working capital.
🌐 Local transfer network, not multi-hop SWIFT chains, is how Aspire routes most payments. This means faster settlement and fewer intermediary fees eating into your payment before it reaches the recipient. It also reduces the chance of funds being held up for review at a correspondent bank along the way.
💸 Fixed USD 8 inbound SWIFT fee, tracked end-to-end with SWIFT GPI, applies when SWIFT is the right rail for your payment. There are no surprise deductions from correspondent banks along the way, so the amount you're quoted is the amount that arrives. You can also download payment confirmation instantly from the app, without calling the bank.
⚡ Approved in as little as 1 business day, with no branch visits and no paperwork stacks. Applications are completed entirely online, from document upload to approval. There's no waiting weeks on a relationship manager to call you back.
Open a free multi-currency business account built for Hong Kong SMEs, or explore how Aspire's corporate card fits into your day-to-day spend.
Frequently Asked Questions
They are services that move money between countries and currencies. Examples include multi-currency accounts, bank wires and payment gateways.
They use a multi-currency account, a bank wire or a transfer service. Our same-day transfers cover 40+ currencies.
Use local account details or a payment gateway. Wise states a one-time HKD 199 fee for local account details.⁵
Transfer, FX and receiving fees apply, depending on the provider. HSBC states HKD 125 for an online outward TT to most destinations.⁸
They are safe when the provider and controls are right. Use payee checks, approvals and user permissions.
It depends on the route. We offer same-day transfers in 40+ currencies, while SWIFT payments can take 1 to 5 business days.
Sources
- PayPal Hong Kong, "Merchant fees" (issuer page, accessed November 2026)
- Stripe, "Pricing" (issuer page, prices stated for Hong Kong SAR, accessed November 2026)
- Airwallex Hong Kong, "Fee schedule" (issuer page, last updated 10 October 2026)
- Airwallex Hong Kong, "Transfers" (issuer page, accessed November 2026)
- Wise, "Business pricing: receive" (issuer page for Hong Kong, accessed November 2026)
- Payoneer, "Pricing" (issuer page, accessed November 2026)
- HKMA, "The Three-tier Banking System"
- HSBC Hong Kong, "Commercial tariffs" (issuer page, August 2026)
- Hang Seng Bank, "Service Charges" (business accounts, effective 1 April 2026)
- DBS Hong Kong, SME payments page (issuer page, accessed November 2026)
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our 'Terms of Service' and 'Pricing' pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Galih Gumelar
Writer
Galih is a seasoned writer specialising in macroeconomics, business, finance and politics. With a writing history at CNN Indonesia, The Jakarta Post, and various other reputed organisations, Galih leverages his broad range of experiences to create insightful resources for those wanting to start a business.
Aspire Launchpad
Start Your Business with Aspire Launchpad
From incorporation to venture capital, we connect you with trusted service providers to make your entrpreneurial journey seamless.

Latest articles
Incorporation •
EOR Services in HK: How They Work and Cost
Understand EOR services in Hong Kong: how an employer of record works, what it costs, which HK rules it handles and how to choose a provider.
Expense Management •
Corporate Card Management in HK: Guide & Policy Checklist
Master corporate card management in Hong Kong. Implement smart spend limits, leverage virtual cards, simplify monthly reconciliation, and maintain required records.
Finance Tools •
Virtual Corporate Card in HK: What Is It?
How HK teams use virtual corporate cards: types, safety, FX costs, a provider comparison and a rollout plan with limits per employee, vendor or project.
Start your journey with Aspire
Open your free account