





Routing number vs account number: key differences explained

Content Team
April 16, 2026

Summary
A routing number is a 9-digit code that identifies your bank in the US banking system, while an account number identifies your specific account at that bank. Both are required for electronic payments like direct deposits, ACH transfers, and wire transfers
Routing numbers are standardized at exactly 9 digits and are shared by all customers at the same bank or branch. Account numbers vary in length (typically 8–12 digits) and are unique to your individual account
On a check, the routing number appears first (bottom left), the account number appears second (middle), and the check number appears third (bottom right). This order reflects how payments are processed: routing to the bank first, then to your account
Large banks often have multiple routing numbers based on the state where you opened your account or the transaction type. Some banks use different routing numbers for ACH transfers versus wire transfers, so always verify which number to use for your specific transaction
Routing numbers are public information that banks publish on their websites, but account numbers are private and need protection. Never share your account number publicly, always verify recipients before providing it, and use secure channels when transmitting banking details
Routing numbers are public information that banks publish on their websites, but account numbers are private and need protection. Never share your account number publicly, always verify recipients before providing it, and use secure channels when transmitting banking details
If you've ever set up direct deposit, paid a vendor via ACH, or wired money to a contractor, you've been asked for your routing number and account number. Most founders copy these numbers from a check without understanding what they actually control.
That works until something goes wrong. Understanding the difference between routing number vs account number isn't just useful. It's necessary if you're running financial operations for your business.
Here you will find what each number does, where to find them, and when you need each one for payments, transfers, and banking operations.
Routing number vs account number: key differences
The easiest way to understand the difference between routing numbers and account numbers is to compare them directly.
| Feature | Routing number | Account number |
|---|---|---|
| Purpose | Identifies the bank or credit union | Identifies your specific account at that bank |
| What it identifies | Financial institution | Individual account holder |
| Number format | Always 9 digits | Varies by bank (typically 8–12 digits) |
| Standardization | Standardized across all US banks | No standard format or length |
| Where it appears | First number on bottom of check | Second number on bottom of check |
| Uniqueness | Shared by all customers at the same bank (or branch) | Unique to your account only |
| When it's used | Required for all electronic transfers | Required for all electronic transfers |
| Public information | Often published publicly by banks | Private and confidential |
The key difference: routing numbers are shared across many customers at the same bank, while account numbers are unique to you. Both are required for electronic payments to work.
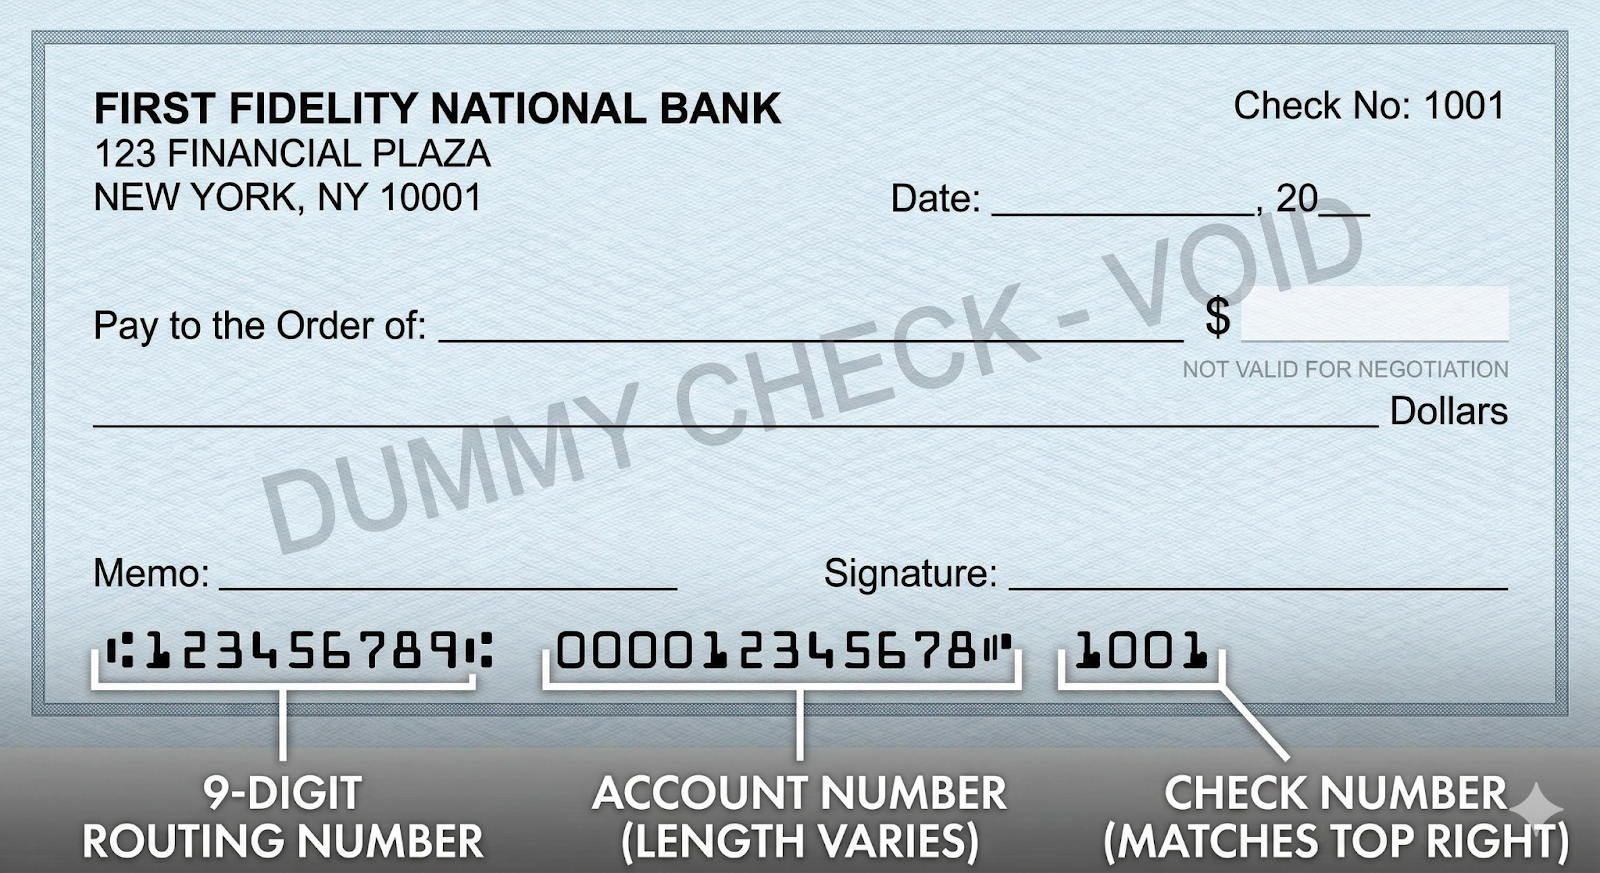
Given above is a quick sample to help you find these numbers.
What is a routing number on check?
A routing number is a 9-digit code that identifies your bank or credit union within the US banking system. It tells the financial network which institution holds your account so payments can be routed to the correct bank.
You can think of it in terms of a bank's address. When you make a payment using an ACH transfer or a wire transfer, the routing number is essentially sending that payment to the proper financial institution. And then within that financial institution, the account number is sending that payment to the proper account.
Where to find your routing number on check
The easiest place to find your routing number is on a check. It's the first 9-digit number on the bottom left, before your account number.
You can also find it by:
- Logging into your online banking portal (usually under account details)
- Opening your bank's mobile app (typically in account settings)
- Checking your monthly bank statement (often listed at the top)
- Calling your bank directly
- Searching your bank's website (most banks publish routing numbers publicly)
What routing numbers identify
Routing numbers identify:
- Your bank or credit union within the US banking system
- Which financial institution holds your account
- Where payments should be routed before reaching your specific account
Why routing numbers matter in banking.
Routing numbers handle the first step in any electronic payment: getting money to the right bank. Without the correct routing number, the payment can't reach your bank at all. It gets rejected before it even attempts to hit your account.
The US has over 4,000 banks and credit unions. The routing number is how the payment network distinguishes one institution from another and ensures funds arrive at the correct bank before the account number takes over to direct them to your specific account.
How many digits are in a routing number
Routing numbers are always exactly 9 digits. This format is standardized across all US banks and credit unions.
The first 4 digits identify the Federal Reserve routing symbol, which indicates the bank's location and Federal Reserve district. The next 4 digits identify the specific bank. The last digit is a checksum used to verify the routing number is valid.
This 9-digit format has been standard since 1910 when the American Bankers Association created the system to streamline check processing.
Understanding routing number format
The routing number has the following structure: XXXXYYYYC, where there are 9 digits in total.
The first 4 digits, XXXX, indicate the Federal Reserve Routing Symbol, which reveals the Federal Reserve District and Institution Type.
The first 2 digits of the routing number range between 01-12 for primary banks, 21-32 for thrift institutions such as credit unions, and 61-72 for electronic payment processors.
The next 4 digits, YYYY, indicate the financial institution, while the final digit, C, is the check digit, which reduces the possibility of misrouted funds due to typos and other numerical mistakes.
| Primary (01-12) | Thrift (+20) | Electronic (+60) | Federal Reserve Bank |
|---|---|---|---|
| 01 | 21 | 61 | Boston |
| 02 | 22 | 62 | New York |
| 03 | 23 | 63 | Philadelphia |
| 04 | 24 | 64 | Cleveland |
| 05 | 25 | 65 | Richmond |
| 06 | 26 | 66 | Atlanta |
| 07 | 27 | 67 | Chicago |
| 08 | 28 | 68 | St. Louis |
| 09 | 29 | 69 | Minneapolis |
| 10 | 30 | 70 | Kansas City |
| 11 | 31 | 71 | Dallas |
| 12 | 32 | 72 | San Francisco |
Source - https://www.routingnumber.com/
For example, 111000038 belongs to the Federal Reserve Bank in Minneapolis. The check digit ensures the number is mathematically valid before processing any payment.
Most founders never need to understand this structure, but it explains why entering even one wrong digit causes payment failures.
Large banks often have multiple routing numbers depending on the state where you opened your account or the type of transaction. For example, Bank of America has different routing numbers for accounts opened in California versus New York. Wire transfer routing numbers can also differ from ACH routing numbers at some institutions.
What is an account number on check?
An account number on check is the unique identifier for your specific bank account. While a routing number points to your bank, the account number points to your individual account within that bank.
No two accounts at the same bank share the same account number. It's how the bank distinguishes your account from the thousands or millions of other accounts they manage.
Where to find your account number on check
Your account number appears on checks as the second set of numbers on the bottom, between the routing number and the check number.
Other places to find it:
- Online banking under account details
- Your bank's mobile app
- Monthly bank statements
- Deposit slips
- By calling your bank's customer service line
What account numbers identify
Account numbers identify:
- Your specific checking or savings account
- The account holder or business entity
- Where funds should be deposited or withdrawn from
If the routing number is the bank's address, the account number is your apartment number within that building. Both are required to complete a payment.
Why account numbers matter in banking
Account numbers ensure payments reach the correct account. Even if the routing number successfully directs a payment to the right bank, the account number determines whether the money lands in your account or someone else's.
Transposing even one digit in your account number can send payments to the wrong account or cause the transaction to fail entirely. Banks can reverse some mistakes, but it requires manual intervention and can delay payments by days or weeks.
How many digits are in a bank account number
Account numbers vary in length depending on the bank. Most range from 8 to 12 digits, though some banks use as few as 5 or as many as 17. There's no standard format across institutions.
When routing numbers and account numbers are used
Both numbers are required for most electronic payments, but the context varies.
Direct deposits
When you set up direct deposit for payroll or customer payments, you need to provide both your routing number and account number. Employers, clients, and payment platforms all use the same information: routing number first, account number second.
ACH transfers
ACH transfers require both numbers. Whether you're sending or receiving money via ACH, the routing number identifies the bank and the account number identifies the account. ACH is the most common form of electronic payment in the US. Payroll, vendor payments, subscription billing, and tax refunds all run through ACH networks.
Wire transfers
For domestic wire transfers, you will need to provide your routing number and account number. However, some banks have a different routing number for wire transfers than for ACH transactions, so be sure to check with your bank to determine the routing number to use.
For international wire transfers, routing numbers are often not necessary and SWIFT numbers or IBAN numbers will be used depending on the country.
Bill payments
When you set up automatic bill payments through your bank or a service provider, you provide your routing and account numbers. The payment processor uses these to debit your account on the scheduled date.
Here's when each number is required:
| Payment type | Routing number required | Account number required | Notes |
|---|---|---|---|
| Direct deposit | Yes | Yes | Most common for payroll |
| ACH transfer | Yes | Yes | Used for vendor payments and bill pay |
| Domestic wire | Yes | Yes | Some banks use a separate wire routing number |
| International wire | Sometimes | Yes | Often uses SWIFT code instead of routing number |
| Bill payment | Yes | Yes | For automated debits from your account |
| Check deposit | No | No | Routing and account numbersare on the check itself |
Why banks use both routing numbers and account numbers
The dual-number system exists because the US banking network needs to route payments through thousands of financial institutions.
The routing number tells the network which bank to send the payment to. Without it, there's no way to know where the money goes. The US has over 4,000 banks and credit unions, and the routing number is how the system distinguishes one from another.
Once the payment reaches the correct bank, the account number directs it to your specific account. A single bank might have millions of accounts, so the account number ensures funds land in the right place.
This two-step system has been the foundation of US electronic payments since the early 1900s. It's why both numbers are required for nearly every transaction.
How to keep your routing and account numbers secure
Routing numbers aren't secret. Banks publish them on their websites. You can Google "Chase routing number" right now and find it in seconds.
Account numbers are different. That's the private half of the equation, and losing control of it creates real problems.
Don't share your account number publicly
This sounds obvious, but founders do it all the time. Posting a screenshot of a payment confirmation on social media. Sending account details in a Slack channel with contractors you barely know. Including banking info in a public Google Doc for "the team."
If it's online and accessible to people you don't personally trust, don't put your account number there.
Verify recipients before sharing
A vendor emails asking for updated banking details. Seems routine. Except the email address is slightly off, by one character different from their real domain. You send the info. Now someone you've never met has full access to pull money from your account.
Before you share account numbers, verify who's asking. Call them directly using a number you already have, not one from the email. If it's a new vendor, confirm their legitimacy through multiple channels.
Use secure channels
Regular email isn't encrypted. If you're sending account details through either, you're sending them in plain text across the internet.
Use your bank's secure messaging system. Use encrypted email if your recipient supports it. At minimum, split the information across two separate messages sent through different channels—routing number in one, account number in another.
Monitor your account regularly
Most fraud gets caught because someone notices a transaction that doesn't belong. Set up alerts for debits over a certain amount. Check your account every few days, not once a month when the statement arrives.
The faster you catch unauthorized activity, the easier it is to reverse.
Be cautious with ACH authorizations
When you share your routing number and account number with someone for the purpose of ACH, you're not simply giving them permission to make one transaction from your account. You're giving them the ability to take money from your account as many times as they wish, in whatever amounts they wish, until such time as you revoke that permission.
Don't share your routing number/account number with just anybody. The random contractor you hired through Upwork last week? Not so much.
Shred old checks and statements
Tearing a check in half and tossing it in the trash isn't enough. Your account number is still readable. Anyone with access to your garbage now has access to your banking details.
Shred checks, statements, and any documents with account numbers before you throw them away. Or burn them if you don't have a shredder.
If your account number gets compromised, contact your bank immediately. They can freeze the account, reverse fraudulent transactions if caught quickly enough, and issue a new account number. It's a hassle, but it's better than watching your balance drain while you're trying to figure out what happened.
Open a business account built for payments
Once you understand routing and account numbers, you need banking infrastructure that actually works for business operations. Aspire1 offers business accounts1 designed for founders managing vendor payments, payroll, and transfers without traditional banking friction.
Multi-currency support*, faster settlement times, and accounting integrations that sync automatically mean you spend less time on banking admin and more time running your business. Open an account in minutes and get the routing and account numbers you need to start processing payments immediately.
Open an Aspire account and simplify how you handle business payments.
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our ’Terms of Service’ and ’Pricing’ pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Content Team
Aspire editorial
Content team at Aspire is a society of seasoned writers & experts specialising in finance, technology and SaaS space. With 50+ years of collective experience, they help make business finance more profitable for readers. They write about finance tools, finance insights, industry trends, tactical guides to grow your business & also all things Aspire.
Aspire Launchpad
Supercharge your finance operations with Aspire
Find out how Aspire can help you speed up your end-to-end finance processes from payments to expense management.

Latest articles

Business Account • Sep 15th, 2026
Live Oak business checking account: features, fees & alternatives
Live Oak Bank business checking review: features, fees, account types, and how it compares to Mercury, Brex, and traditional banks for small businesses.

Business Advice • Sep 15th, 2026
Employer of Record (EOR): what it is, how it works, and when to use one
An Employer of Record (EOR) lets you hire and pay talent abroad without a local entity. Learn how an EOR works, EOR vs PEO, and when to use one.

Business Advice • Sep 15th, 2026
7 best Relay alternatives for US businesses in 2026
Searching for a Relay alternative? Compare Aspire, Bluevine, and Mercury on interest rates, lending, cash deposits, and international payments.