

Top 8 Fintech Digital Payment Solutions in HK
Galih Gumelar

Summary
Digital payments do 3 jobs. They collect money from customers, pay suppliers and staff, and manage spend.
Usage is large and growing. The HKMA counted 90.38 million SVF accounts in use at the end of Q2 2026.¹
8 top fintech and wallet options handle collection. Aspire payment links, PayMe for Business, Airwallex, Stripe, PayPal, Adyen, Checkout.com and AlipayHK each state different terms.
Fees differ by rail and card type. Airwallex states 3.30% for domestic cards and 1.00% for WeChat Pay.²
Reconciliation links the tools. A single account that receives, pays and records money cuts manual matching.
Digital payment solutions are the tools a business uses to collect, send and spend money electronically. In Hong Kong, they range from FPS transfers and e-wallets to payment links, bulk payment files and corporate cards.
This guide sorts the main options by the job they do. It compares 8 top fintech and wallet solutions for collecting payments, then shows how a business can connect them and choose well.
What are digital payment solutions in HK?
Digital payment solutions are services that move money electronically instead of by cash or cheque. They include bank transfers, e-wallets, card acceptance, payment links, bulk files and cards.
Our guide to what an e-payment is covers the definition in depth. This guide focuses on choosing and connecting the tools.
Which digital payment types exist in HK?
Hong Kong businesses use digital payments for 3 jobs: collecting, paying and spending. The table maps each job to its solution types and to our deeper guide.
| Job | Solution types | Read more |
|---|---|---|
| Collect | FPS, QR codes, e-wallets, card acceptance, payment links | HK mobile payment guide and payment methods in Hong Kong |
| Pay | Bulk files, FPS, local and SWIFT transfers | B2B payment methods |
| Spend | Corporate and virtual cards, mobile wallets | Our corporate card |
How widely are digital payments used in HK?
The HKMA reports that SVF usage keeps growing, while spending value has dipped. The diagram shows the Q2 2026 figures.¹
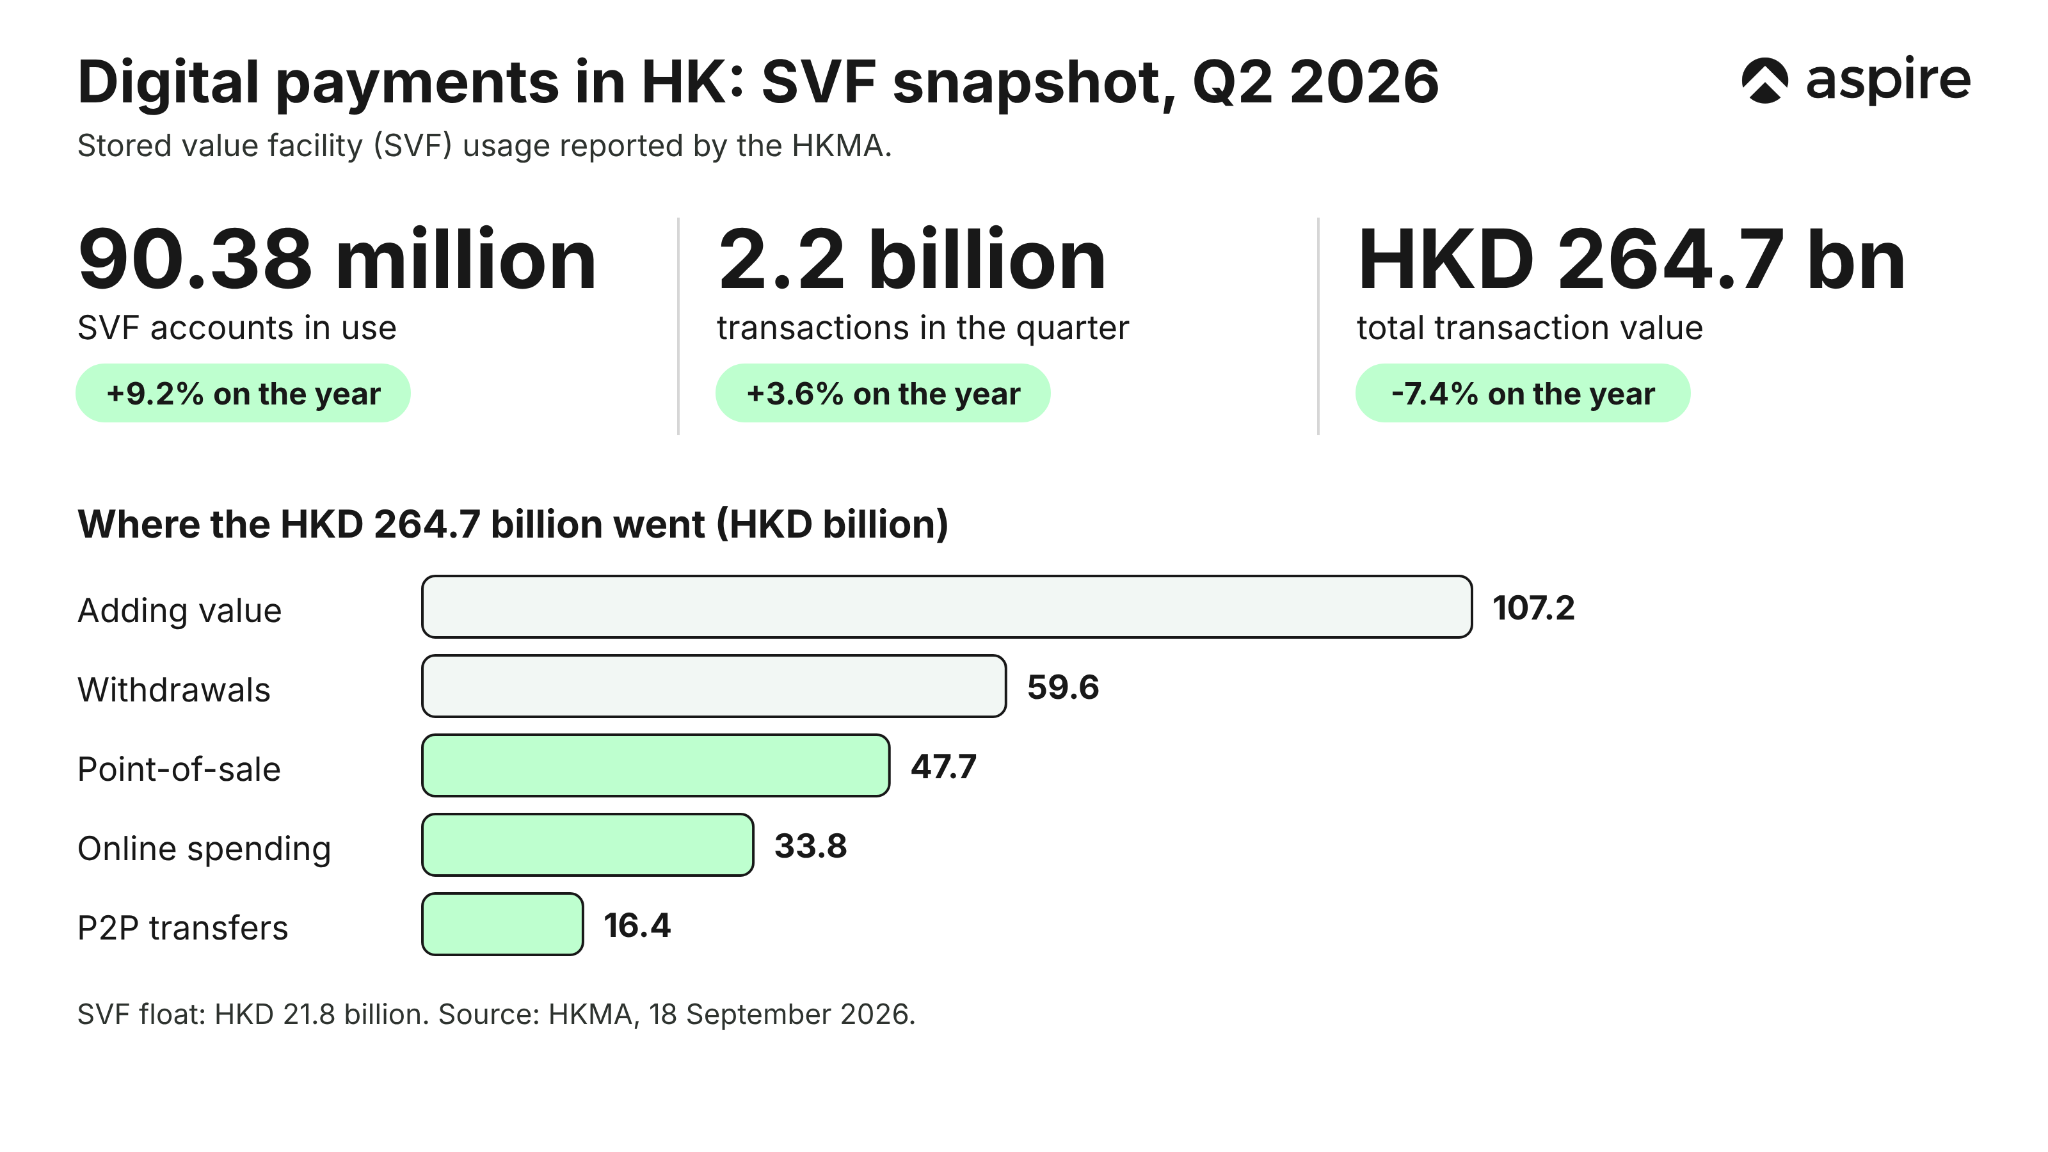
Accounts rose 9.2% on the year and transactions rose 3.6%, but transaction value fell 7.4%.¹ Wallets are used for small, frequent payments, so more activity does not always mean more value.
FPS adds to this picture. It launched in September 2018 and handled about 1.25 million transactions a day in 2023.³
Why does this list focus on fintech?
This list covers fintech and wallet providers, not traditional banks. Banks also offer digital payments, such as FPS transfers and bulk payment files.
Our bulk payment guide compares DBS and HSBC, and our global payment guide explains how fintechs differ from banks. PayMe for Business is the 1 bank-backed wallet here, so we include it as a wallet product.
Which are the top digital payment solutions?
These 8 fintech and wallet solutions state how they collect payments, and we list ours first. The table shows what each states, and fees change, so check current terms.
| Solution | How it collects | Fee stated | Not stated |
|---|---|---|---|
| Aspire payment links | Send a link by email, social media or messaging apps from your HKD or USD account | Not stated | Fees and HKD settlement time |
| PayMe for Business | PayCodes or PayLinks, face to face or remotely⁴ | 1.2% in the app, 1.5% through the API⁴ | Settlement timing⁴ |
| Airwallex | Checkout, Payment Links, plugins and an API for cards and local payment methods⁵ | 3.30% domestic cards, 3.60% international cards, 1.00% WeChat Pay² | Settlement timing⁵ |
| Stripe | Cards and wallets through a gateway connected to our account | 3.4% + HKD 2.35 domestic cards; +0.5% international cards; +2% if currency conversion is needed⁶ | Settlement timing |
| PayPal | Standard commercial payments and QR Code payments⁷ | 3.90% + HKD 2.35 standard, 2.90% + HKD 2.35 for QR Code; cross-border adds 0.50 percentage points⁷ | Settlement timing |
| Adyen | Gateway connected to our account | Not stated | Fees and settlement |
| Checkout.com | Gateway connected to our account | Not stated | Fees and settlement |
| AlipayHK | An online payment option on your website or app⁸ | Not stated | Fees and settlement⁸ |
Airwallex adds a gateway fee of HKD 2.35 per card transaction and HKD 2.00 per local method transaction.² PayPal converts balances at 3.00% above the base exchange rate, and 4.00% for other conversions.⁷ PayMe for Business is open to HSBC Business Internet Banking users.⁴
Adyen and Checkout.com publish no Hong Kong rates in the pages we link. Ask each provider for current pricing before you choose.
Our guides explain the 2 wallet options in detail: PayMe for Business and AlipayHK for merchants.
How do you pay suppliers and staff?
You pay suppliers and staff digitally by uploading 1 file that pays many recipients. The same file works for invoices, freelancers and salaries.
Our bulk payments pay thousands of destinations from 1 CSV file, and our bulk payment solution guide compares the options. For salaries, see our guide to payroll processing.
The HKMA says companies can pay salaries through FPS using HKID numbers.³
How do you manage spend digitally?
You manage spend digitally with corporate cards, virtual cards and mobile wallets. Our card can be added to Apple Pay and Google Pay for online and offline payments.
We also let Hong Kong customers pay MPF contributions from the account. Spend then lands in 1 place, which makes reconciliation faster.
What does a card add to wallets?
A corporate card gives each team member their own limit and a receipt trail. Founders no longer pay for software or ads from a personal card, so month-end matching is shorter.
Our corporate card works with the wallets staff already carry.
How does a HK business run digital payments?
A business connects the tools into 1 cycle: collect, hold, pay, spend and reconcile. The diagram shows the cycle.
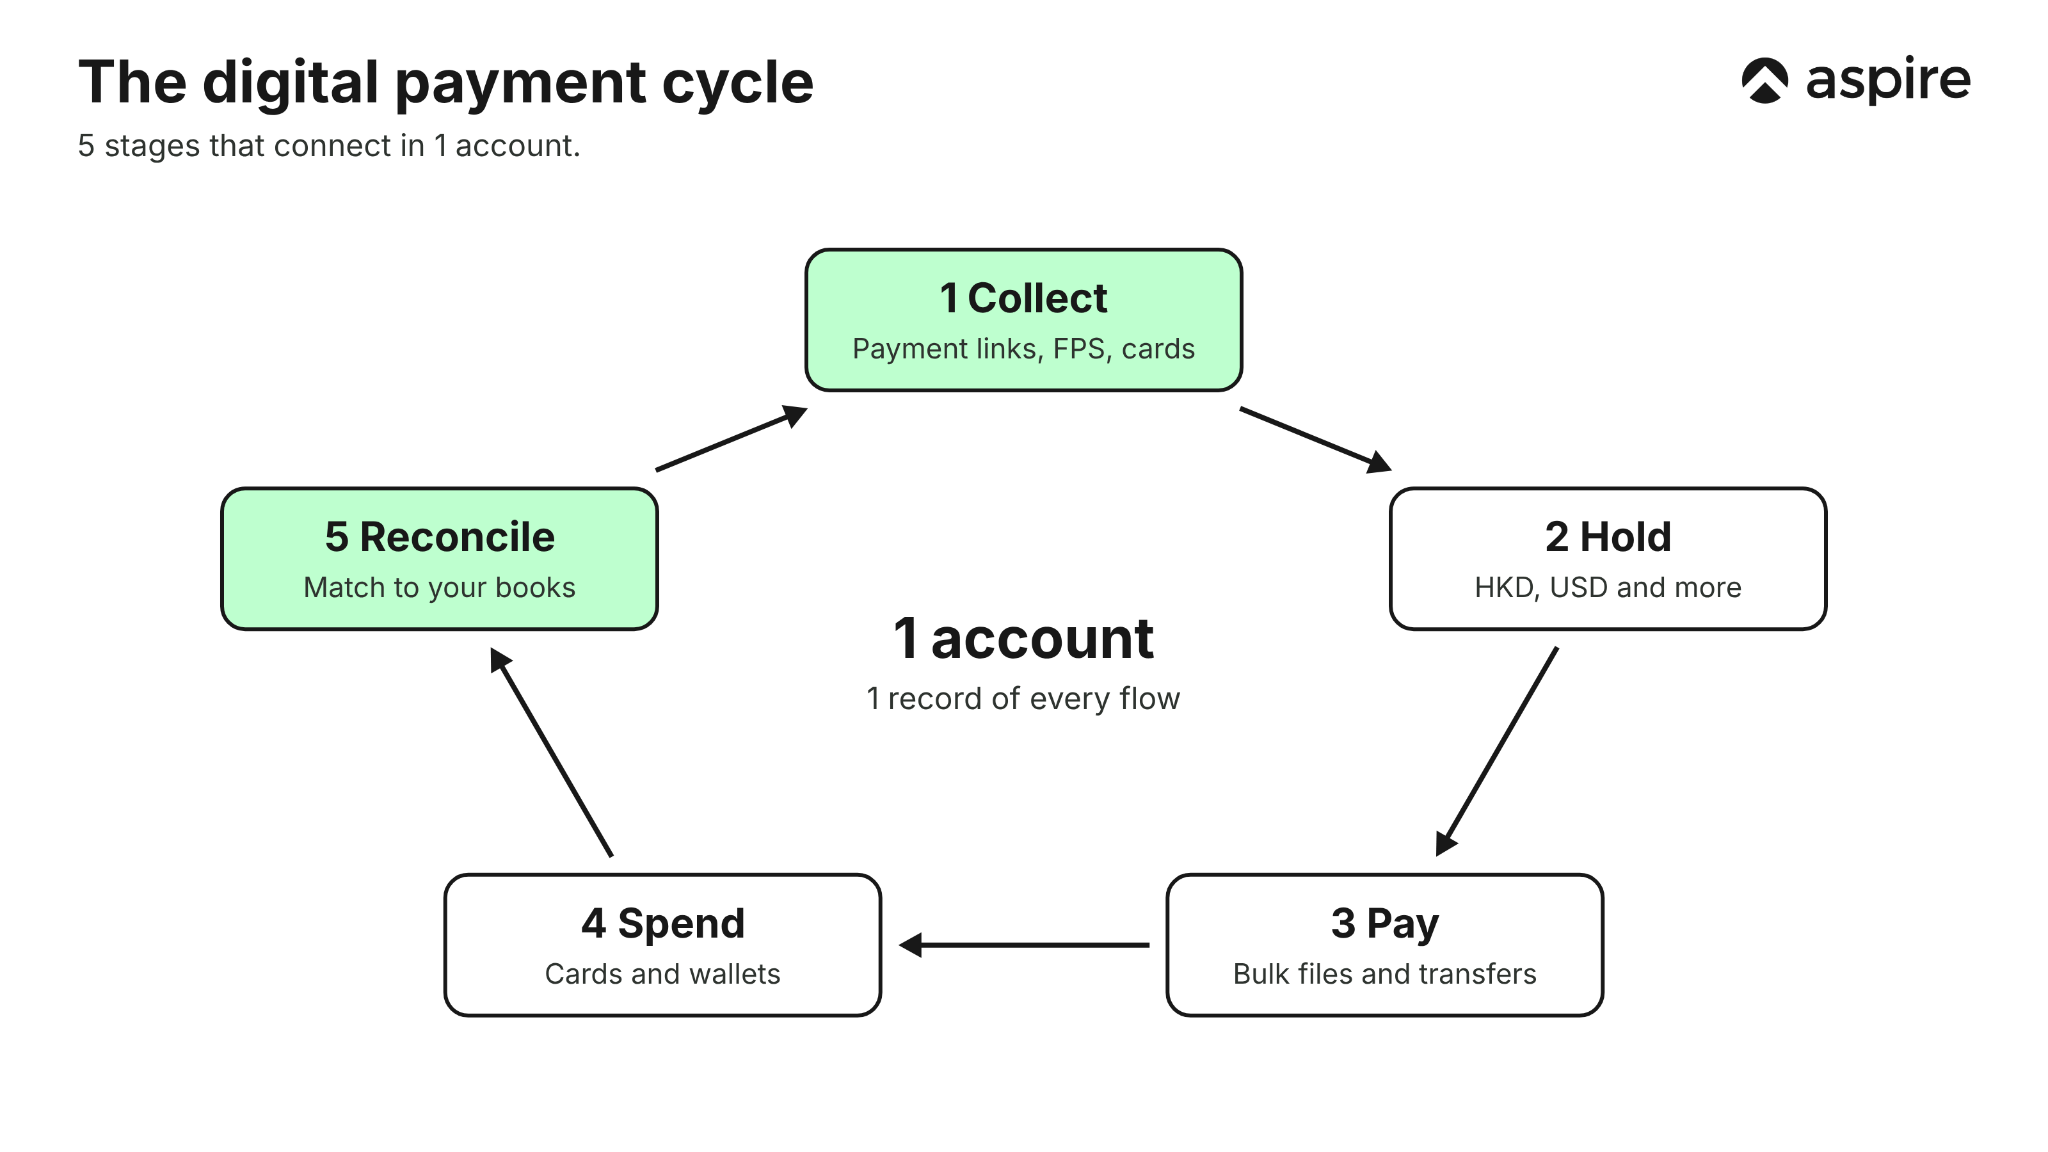
This illustrative example uses a Hong Kong online florist. All names and figures are invented.
| Step | Monthly amount |
|---|---|
| Collected through payment links | HKD 80,000 |
| Paid to growers in 1 batch | HKD 30,000 |
| Paid in salaries | HKD 25,000 |
| Spent on ads by card | HKD 5,000 |
| Left in the account | HKD 20,000 |
The florist reconciles 4 flows against 1 account instead of 4 separate records. Our integrations connect the account to Xero and other accounting tools.
How do you choose a payment solution?
Choose on the rail, the fee, the settlement time and the controls. Use this 6-point checklist.
- Job. Decide whether you collect, pay or spend.
- Fee. Compare the fee for your card mix and amounts.
- Settlement. Ask when funds reach your account.
- Currency. Check which currencies you can receive and hold.
- Accounting. Confirm that payments sync to your books.
- Controls. Look for approvals and user permissions.
What risks come with digital payments?
The main risks are fraud, payee errors and fee surprises. Check these 4 points.
- Payee errors. Verify account names before every batch.
- Fraud checks. Confirm every new payee through a second channel before you send the first payment.
- Fee gaps. Ask for the full fee schedule, including gateway and refund fees.
- Access. Give each user only the permissions they need.
How do we support digital payments?
We help Hong Kong businesses collect, pay and spend from 1 account. Our payment links let Admin and Finance users create a link and share it by email, social media or messaging apps.
- Collect. Send payment links from your HKD or USD account.
- Integrate. Connect Xero, Stripe, PayPal, Payoneer, Adyen and Checkout.
- Pay. Run bulk payments, or automate mass payments and webhooks through our API.
- Spend. Use our card with Apple Pay and Google Pay.
- Reconcile. Keep payments, cards and transfers in 1 account.
Why Hong Kong Businesses Choose Aspire
Digital payments cover collecting, paying and spending money, and Aspire supports the accounts, cards and transfers that connect them.
💱 FX spreads from 0.18%, up to 3x cheaper than traditional banks. This applies across 130+ countries and 40+ currencies through Aspire's multi-currency account. It's useful for anything from paying overseas suppliers to settling international payments without losing margin to markup.
💰 1.2% unlimited cashback applies on every corporate card transaction, with no monthly cap. It kicks in automatically on eligible spend, with no minimum threshold to hit first. Over time, it quietly turns routine business spend into working capital.
🌐 Local transfer network, not multi-hop SWIFT chains, is how Aspire routes most payments. This means faster settlement and fewer intermediary fees eating into your payment before it reaches the recipient. It also reduces the chance of funds being held up for review at a correspondent bank along the way.
💸 Fixed USD 8 inbound SWIFT fee, tracked end-to-end with SWIFT GPI, applies when SWIFT is the right rail for your payment. There are no surprise deductions from correspondent banks along the way, so the amount you're quoted is the amount that arrives. You can also download payment confirmation instantly from the app, without calling the bank.
⚡ Approved in as little as 1 business day, with no branch visits and no paperwork stacks. Applications are completed entirely online, from document upload to approval. There's no waiting weeks on a relationship manager to call you back.
Open a free multi-currency business account built for Hong Kong SMEs, or explore how Aspire's corporate card fits into your day-to-day spend.
Frequently Asked Questions
Digital payment solutions are tools that move money electronically. They collect, send and spend business money.
FPS, e-wallets such as PayMe and AlipayHK, cards and payment links are common. The HKMA reported 90.38 million SVF accounts in use at the end of Q2 2026.¹
They send payment links or use a wallet or card service. Fees and settlement terms differ, so compare them first.
They are safe when the tools and controls are right. Use payee checks, approvals and user permissions.
Yes. A bulk file pays many suppliers in a single batch.
It depends on the provider. Airwallex states 3.30% for domestic cards and 3.60% for international cards.²
Sources
- HKMA, "Statistics of Stored Value Facilities (SVF) Schemes Issued by SVF Licensees" (press release, 18 September 2026)
- Airwallex Hong Kong, "Fee schedule" (issuer page, last updated 10 October 2026)
- HKMA, "The Faster Payment System: transcending boundaries and connecting with everyday lives" (27 March 2024)
- HSBC Hong Kong, "PayMe for Business" (issuer page, accessed November 2026)
- Airwallex Hong Kong, "Payments" (issuer page, accessed November 2026)
- Stripe, "Pricing" (issuer page, prices stated for Hong Kong SAR, accessed November 2026)
- PayPal Hong Kong, "Merchant fees" (issuer page, accessed November 2026)
- AlipayHK, "Merchants" (issuer page, accessed November 2026)
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our 'Terms of Service' and 'Pricing' pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Galih Gumelar
Writer
Galih is a seasoned writer specialising in macroeconomics, business, finance and politics. With a writing history at CNN Indonesia, The Jakarta Post, and various other reputed organisations, Galih leverages his broad range of experiences to create insightful resources for those wanting to start a business.
Aspire Launchpad
Start Your Business with Aspire Launchpad
From incorporation to venture capital, we connect you with trusted service providers to make your entrpreneurial journey seamless.

Latest articles
Incorporation •
EOR Services in HK: How They Work and Cost
Understand EOR services in Hong Kong: how an employer of record works, what it costs, which HK rules it handles and how to choose a provider.
Finance Tools •
Top 6 Fintech Global Payment Solutions for HK Businesses
Compare 6 top fintech global payment solutions for HK businesses and how they differ from banks: stated fees, speeds and a checklist to choose well.
Expense Management •
Corporate Card Management in HK: Guide & Policy Checklist
Master corporate card management in Hong Kong. Implement smart spend limits, leverage virtual cards, simplify monthly reconciliation, and maintain required records.
Start your journey with Aspire
Open your free account