Cross-border payments: a founder's complete guide

Content Team

Summary
Cross-border payments are an integral part of global businesses, but traditional banking can be slow, expensive, and opaque
Many international transfers process payments through intermediary banks, which often include hidden deductions and take 2 to 5 days to settle
The four biggest roadblocks are high fees, FX volatility, slow payments, and compliance delays
Founders often overpay by focusing on wire fees instead of the true cost (FX markup + intermediary charges)
Regulatory changes like ISO 20022 are improving payment data quality, reducing errors and failures
Multi-currency accounts and local payment rails help reduce conversions, costs, and delays
Keeping KYC and beneficiary details updated prevents avoidable transfer holds
Founders who optimize cross-border payments early build faster, cheaper, and more scalable global finance operations
One Aspire account to manage your business finances in one place.
Get a business account¹, issue corporate cards², manage expenses, and automate financial workflows, all from one powerful platform built for modern businesses.
When an overseas supplier receives less than what you sent due to unitemized deductions, you experience the core friction of legacy cross-border payments. The system was built for banks, not founders, and it has been running on the same logic for decades.
But building a global business today means making cross-border payments constantly, whether you are paying vendors in Europe, collecting revenue from customers in the US, or running payroll for a team spread across time zones. The fees, the FX surprises, and the compliance holds are real costs that compound every time you move money across a border.
This blog covers how cross-border payments work, the challenges that hit your margins, what the latest regulations mean for you, and a practical framework for setting up international payments that do not slow you down.
What are cross-border payments
In simple terms, a cross-border payment is the transfer of funds from one nation to another. You are most likely already doing this in various ways if you are developing a business. This includes paying a foreign supplier, receiving payment from a foreign client, managing payroll for a remote team, sending invoices in multiple currencies, and even receiving money from foreign investors. You are simultaneously dealing with various currencies, banking systems, and regulations.
How cross-border payments work
Moving funds internationally rarely happens in a straight line. Traditional cross-border payments for banks rely on legacy SWIFT messaging networks and correspondent chains. Modern transaction platforms bypass these layers by utilizing local payout rails, internal ledger movements, or direct banking relationships. Learning how international payments and merchant processing work helps you avoid extra fees and settle global invoices faster:
1. Sender initiates the payment with the desired amount, currency, and recipient details.
2. The payment provider validates the payment instructions and beneficiary details.
3. The provider determines the best routing method for the transfer.
4. FX conversion occurs if currencies need to be swapped.
5. The payment travels through a correspondent bank, card network, or local payout route.
6. The receiving financial institution performs final compliance checks.
7. The recipient receives the funds in their account.
Note: Not every cross-border payment follows every step.
Traditional international transfers rely on SWIFT messaging and correspondent banking chains when banks lack a direct relationship. Selected intermediary links can introduce extra fees and processing delays, turning what should be a simple transfer into a slower, more expensive process.
While SWIFT payment often delivers payments quickly, end-to-end processing - including intermediary handling and final-mile local bank crediting - frequently takes 2 to 5 business days. Modern payment platforms that connect directly to local rails bypass most of this chain.
Types of cross-border payments
Cross-border transactions generally fall into a few distinct categories depending on who is sending and receiving the funds:
| Payment type | Description |
|---|---|
| Business-to-Business (B2B) | Commercial transfers to international suppliers, vendors, or subsidiaries. Requires high-volume tracking and compliance. |
| Business-to-Consumer (B2C) | Payments to individuals abroad, such as payroll, freelance disbursements, and refunds. |
| Consumer-to-Business (C2B) | Inbound payments from international customers via global card networks, digital wallets, or local rails. |
| Person-to-Person (P2P) / Remittances | Consumer-to-consumer transfers. Founders should prioritize business-grade accounts for higher volumes and compliance. |
How much do cross-border payments cost
The cost of a cross-border payment typically ranges between 3% and 7% of the total transaction value. However, these figures are not universal. It largely depends on the payment method, the countries involved, and the volume of transactions.
| Payment rail | Typical all-in effective rate | Key cost factors |
|---|---|---|
| Virtual Multi-Currency Export Accounts | 0.5% to 1.2% | Lowest cost for B2B/freelance invoices; near mid-market rates. |
| SWIFT Bank Wires (Traditional) | 1% to 4% | Base wire charges plus flat intermediary bank correspondent fees (USD $15-USD $50). |
| International Card Gateways | 3.5% to 6.0% | Includes Merchant Discount Rates (MDR) plus hidden FX markup spreads. |
| Legacy Global Wallet Aggregators | 6.0% to 8.5% | Highest overall friction due to bundled conversion spreads and fixed fees. |
Total cost of a cross-border payment
Don’t compare providers based on the wire fee alone. The true cost of a cross-border payment includes transfer fees, FX spread, intermediary fees, receiving fees, and delay/operational costs.
Looking at the total cost gives you a more accurate picture of what you actually pay - and helps you choose the most cost-effective payment setup for your business.
The cross-border payment challenges every founder faces
As easy cross-border payment sound and feel, they do come with their own set of challenges. These are not abstract problems. They hit your margins, your supplier relationships, and your ability to move at speed. The following are some of the cross-border payment challenges every founder like you may deal with:
1. High fees that are hard to see
When evaluating cross-border payment platforms, look past the headline wire cost to uncover the true total fee. Every B2B cross-border payment fee typically consists of:
- Wire fee: A flat charge per transfer at traditional banks, which varies by bank, country, transfer type, and account.
- FX margin: A percentage markup applied above the real mid-market rate, varying between providers and currencies.
- Intermediary deductions: Correspondent banks taking a cut directly from the principal amount.
- Receiving bank fees: Unpredictable charges applied at the final destination.
2. Transfers that take days when you need hours
For a founder managing tight supply chains or time-sensitive invoices, a 2 to 5 business day international wire transfer creates real operational risk, not just inconvenience.
- Late payments can trigger penalty clauses in supplier contracts
- Compliance holds add another 24 to 72 hours with no explanation given
- Up to 80% of a cross-border payment's total journey time can occur during final-mile processing after it leaves the initial correspondent network.
3. FX moves that affect your margins
When you invoice a US customer for USD $50,000 and the rate shifts before converting to SGD, your margin shrinks. Setting up a cross-border multi-currency payment structure lets you hold balances in local currencies so you control when conversions happen.
- Rate changes between invoice date and payment date can move 1% to 2%, affecting landed costs (this depends on the currencies and timeframe)
- Without multi-currency accounts, every cross-border transaction triggers an unplanned conversion (only when the payer and provider setup lacks local-currency holding capabilities)
- Traditional banks quote rates 1.5% to 5% worse than the real mid-market rate
4. Compliance that differs in every market
If you are sending money from Singapore to the US, and it is finally reaching a supplier in Nigeria, your payment is not just moving across countries; it is passing through three completely different regulatory systems at the same time.
There will be more regulations, more checks, and more opportunities for things to go wrong. The payment can be stopped in the middle by even a minor problem, such as a missing document or a small discrepancy in the recipient's information. And when that occurs, it frequently just sits there with no indication of when it will move once more.
- Different KYC standards across jurisdictions slow down onboarding and individual transfers
- Additional sanctions, AML, fraud, or beneficiary checks can delay processing when more information is required.
- Founders across multiple markets need a provider that handles compliance properly.
Cross-border payment challenges: what they cost founders and how to fix them
| Challenge | What it costs founders | How to fix it |
|---|---|---|
| High fees | Margin loss on every transfer | Use fintech rails with transparent FX. Hold funds in local currencies to cut conversions. |
| Slow settlement | Disrupted supplier payments, damaged relationships | Choose a provider with same-day or real-time international payment capability. |
| FX volatility | Unpredictable costs on every invoice | Hold multi-currency balances. Compare total cost including FX markup, not just the wire fee. |
| Compliance complexity | Frozen transfers, missed deadlines | Work with a provider that handles KYC, AML, and sanctions screening natively. |
Cross-border payments regulation: what changed and what it means for you
Cross-border payment rules have changed quite a bit over the last couple of years. And these changes are not just happening in the background; they directly impact how you send and receive money.
They can affect which platforms you are allowed to use, what kind of documents you need to submit, and even how long your transfers take to go through.
The FSB Policy
The Financial Stability Board (FSB) published its final recommendations in December 2024 to improve consistency and risk-proportionate supervision across bank and non-bank cross-border payment service providers (PSPs). These recommendations are designed to guide international standards rather than act as direct, binding global law. Building on this framework, the FSB launched a new implementation phase in March 2026, calling on member jurisdictions to develop targeted action plans for enhancing cross-border payment systems.
Because cross-border rules vary significantly across nations, the FSB framework focuses on several core areas:
- Regulatory consistency: Aligning supervisory expectations so that similar payment activities face comparable oversight regardless of whether they are conducted by traditional banks or modern fintech platforms.
- Risk assessments and proportional supervision: Ensuring rules match the actual risk profile of the entity rather than imposing blanket requirements.
- Consumer protection: Boosting transparency, safety measures, and recourse options for users sending funds globally.
- Licensing and registration reviews: Encouraging authorities to re-examine how non-bank payment providers are authorized to operate.
- Cross-border regulatory cooperation: Improving information-sharing and reduce regulatory gaps and cross-border compliance frictions.
ISO 20022 and the push for faster settlement, 2026
A major milestone in global payments was reached in November 2025, when SWIFT’s CBPR+ migration ended the coexistence period between traditional MT messages and ISO 20022 for cross-border payment instructions. From 22 November 2025, ISO 20022 became the standard messaging format for these payments, bringing richer and more structured data into the cross-border payment process.
The migration is continuing in 2026, with the next major milestone focused on data quality. SWIFT and other global payments markets are mandating that all cross-border payment messages include structured or hybrid postal addresses (such as dedicated fields for town name and country code). Instead of vague or incomplete data, banks can see exactly who is sending the money, who is receiving it, and why. This means that there is less back-and-forth, fewer errors, and a much lower chance of payments getting stuck.
Cross-border B2B payments: the mistakes founders make
For B2B payments, many avoidable problems come from workflow and provider setup rather than the payment rail itself. Instead of managing restrictive legacy banking relationships, modern businesses use dedicated fintech infrastructure designed for global transactions. The most common mistakes founders make with cross-border B2B payments:
Personal bank accounts
Most consumer transfer tools are not built for B2B volumes. They apply retail FX margins on every payment and give you no visibility into where the money is or why it is late. A business-grade account with transparent FX pricing makes a material difference at volume.
Unverified beneficiary details
Wrong account details are the single biggest cause of failed or delayed B2B transfers. Recalling a payment is slow, expensive, and not guaranteed. Verify account number, routing details, and currency for every new payee before the first transfer, not after one fails.
Unnecessary currency conversions
If you regularly pay suppliers in EUR or USD, holding a balance in those currencies means you convert once, on your terms, at a rate you chose. Converting on every transaction means the rate is always someone else's decision.
Wrong cost comparisons
The wire fee is the smallest number on the invoice. The FX margin, intermediary deductions, and receiving bank fees are where the real cost sits. Always compare total landed cost across your most common corridors before committing to a provider.
Ignoring compliance
When a transfer stalls because of a missing document or a KYC flag, it is your supplier relationship on the line. Own your compliance documentation, keep it current, and use a provider that flags gaps before a transfer is initiated, not after.
Choosing the right cross-border payment setup
The right cross-border payment setup comes down to factors such as where you are sending your money, what currency you are using, the frequency of your payments, and how quickly funds need to arrive.
For example, if your business only occasionally makes international payments, a traditional bank or SWIFT transfer may be better. However, businesses that frequently make cross-border payments may benefit from multi-currency accounts, or a platform that lets them hold and convert currencies without making unnecessary conversions.
When comparing providers, consider:
| Consideration | Action |
|---|---|
| How much cross-border payments cost | Look at the transfer fee, FX markup, intermediary bank charges, and receiving fees - not just the upfront transaction fee. |
| How long payments take | Check expected settlement times for your specific payment corridors. Local rails can often be faster than traditional SWIFT transfers, depending on the countries and currencies involved. |
| Payment methods | Consider whether the provider supports the payment methods your business actually needs, including bank transfers, local rails, and multi-currency payments. |
| SWIFT vs. local rails | SWIFT can provide broad international coverage, while local payment rails may offer faster and more cost-efficient transfers where available. |
| How businesses reduce fees | Holding funds in the currencies you regularly use, avoiding unnecessary conversions, and choosing providers with transparent FX rates can help lower the total cost of international payments. |
| Compliance requirements | Make sure the provider can support the KYC, AML, beneficiary, and transaction documentation requirements that apply to your business and payment corridors. |
Here is the cleaned and merged section that removes the forced phrases, cuts the promotional Aspire specifics, and eliminates the overlap with "Choosing the right cross-border payment setup" by focusing strictly on actionable implementation steps:
How to set up cross-border payments that actually work
To build a global finance operation that protects your margins and avoids unnecessary friction, focus on four core implementation steps:
- Hold balances in the currencies you pay out in most often: Stop repeated FX conversions on every transfer. Converting once at a rate and time of your choosing keeps your margins predictable.
- Choose a provider with direct local payment rail connections: Skip legacy correspondent banking chains. Local rails deliver faster settlement, lower fees, and fewer operational surprises for your teams and suppliers.
- Keep your KYC documents and beneficiary details current: Up-to-date information prevents manual compliance holds and clearance delays.
- Compare the total cost across your most common corridors: Look beyond headline wire fees. Factor in the FX markup, intermediary charges, and receiving fees to understand the true landed cost before committing to a provider.
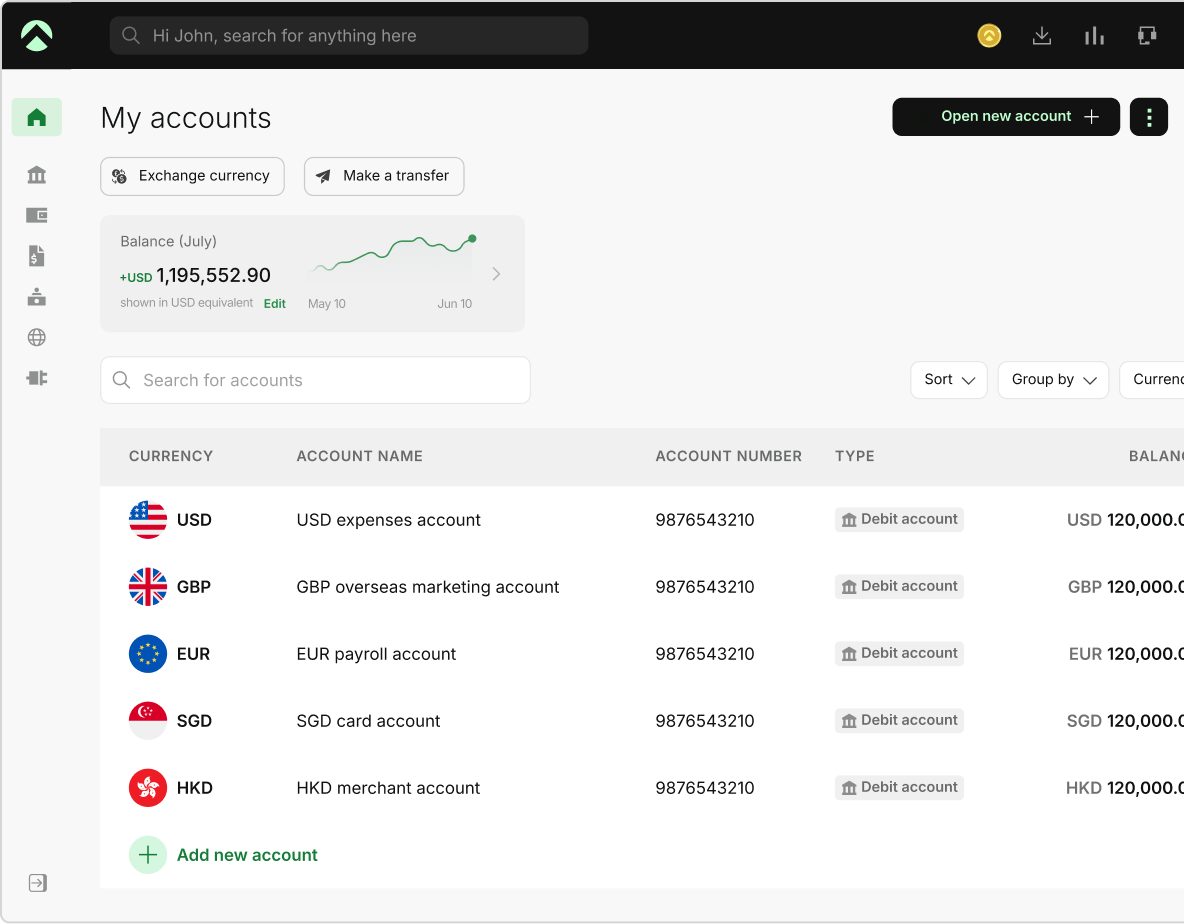
Aspire combines multi-currency accounts, FX, local transfers, and SWIFT payments in one finance platform. Its US Basic plan is currently USD $0/month, supports accounts in 13 currencies, and lists FX pricing from 0.22% above the mid-market rate. SWIFT receiving is currently USD $0, while SWIFT sending is USD $5 for SHA and USD $15 for OUR.
Final thoughts
Cross-border payments* are not a finance problem, but they are a founder problem. Every dollar lost to FX margins, every transfer frozen by a compliance hold, every supplier relationship strained by a late payment: these are business problems with practical, available solutions.
Founders who get this right early build a financial operation that scales with them. The ones who do not are still explaining to suppliers why the invoice amount never seems to land correctly.
Frequently Asked Questions
It just means sending or receiving money between two different countries. That is it. The only difference is that currencies, banks, and rules are not the same on both sides.
You start the payment, and then it travels through a few banks before reaching the other person. Along the way, the money may get converted into another currency and checked for compliance. More steps usually means more time and more fees.
Most people face the same issues. Fees that are not always clear, payments taking longer than expected, exchange rates changing, and a lot of paperwork or checks.
Usually around two to five business days. Sometimes faster, sometimes slower. Delays often happen during checks or right before the money reaches the receiver.
Rules have become stricter, especially for fintech platforms. You might have to share more details when setting things up, but in return, payments are safer and more reliable.
Try to keep money in the currencies you use often, pick providers that have direct connections in the countries you deal with, and always check the total cost, not just the transfer fee.
Yes, Ripple's network (utilizing XRP and its On-Demand Liquidity / Ripple Payments infrastructure) is actively used by businesses and payment providers worldwide to facilitate real-time cross-border settlements and liquidity management.
It is a new standard that helps banks share better, clearer payment information. This reduces errors and makes payments smoother.
They let you hold different currencies in one place. So you do not have to convert money again and again, which saves both time and cost.
Cross-border payments cover any money movement between countries, including business transfers like paying suppliers or running global payroll. Remittances are usually smaller personal transfers, money sent home by individuals to family or friends. As a founder, you’re typically handling cross-border B2B payments, which involve higher volumes and stricter compliance.
Sources
- https://wise.com/in/send-money/ (https://wise.com/in/send-money/), NA
- https://stripe.com/in/resources/more/cross-border-payments-explained , Feb 28, 2025
- https://www.papayaglobal.com/blog/cross-border-payments/ , March 11, 2026
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our ’Terms of Service’ and ’Pricing’ pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Content Team
Aspire editorial
Content team at Aspire is a society of seasoned writers & experts specialising in finance, technology and SaaS space. With 50+ years of collective experience, they help make business finance more profitable for readers. They write about finance tools, finance insights, industry trends, tactical guides to grow your business & also all things Aspire.
Aspire Launchpad
Supercharge your finance operations with Aspire
Find out how Aspire can help you speed up your end-to-end finance processes from payments to expense management.
Latest articles
QuickBooks vs Xero: Key differences, costs and which is better
QuickBooks vs Xero compared on features, pricing, users, reporting, and ease of use. See which accounting software is a better fit for your business.
How general liability vs professional liability insurance works in the US
Small business guide to general liability insurance. Learn about costs and coverage, if you need it, and how to choose the right policy.
Best multi-currency business accounts in the US for 2026
Compare the best multi-currency business accounts in the US for 2026. Explore fees, FX costs, currencies, holding, receiving options, and key features.