Best corporate cards for US businesses in 2026

Content Team

Summary
A corporate card is a company-issued payment card designed to manage spending across employees and departments, often with company-level liability and built-in spend management tools.
The best corporate card for your company depends on what you can qualify for: Ramp asks for USD $25,000 in a linked US bank account, Brex looks for funding or a USD $50,000+ cash balance, and Aspire's secured card sets your limit from a collateral deposit
Our top picks for 2026 are Aspire, Ramp, Brex (now owned by Capital One), Amex Corporate Platinum, and BILL Divvy, each for a different stage of company
Compare 5 things before you apply: personal guarantee, cash requirements, employee spend controls, accounting sync, and total cost per user
Most corporate cards are corporate charge cards that must be paid in full, so they're built for spend control, not for carrying a balance
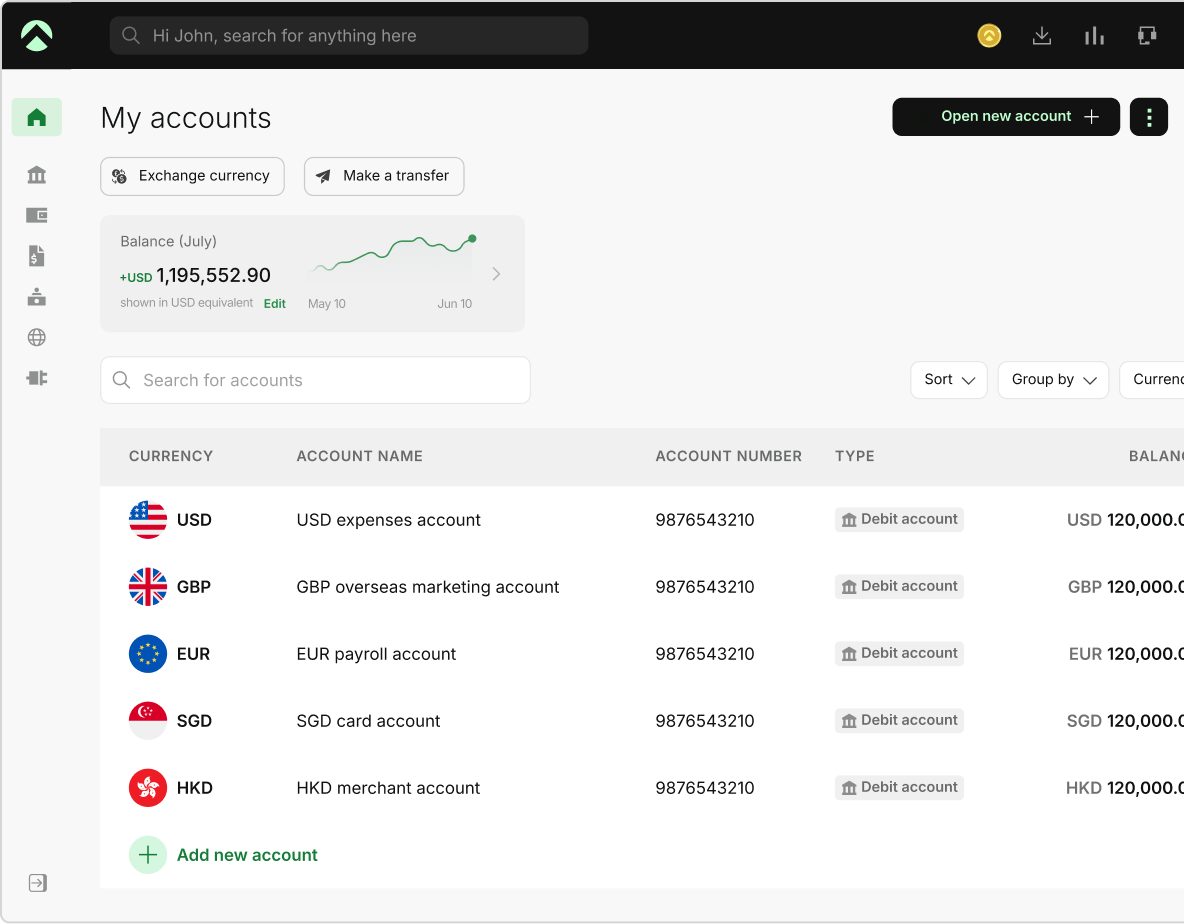
One Aspire account to manage your business finances in one place.
Get a business account¹, issue corporate cards², manage expenses, and automate financial workflows, all from one powerful platform built for modern businesses.
The best corporate card is the one your company can qualify for today that gives every employee a card as you control the limit. For most US-based startups in 2026, that shortlist contains cards from Aspire, Ramp, Brex, Amex Corporate Platinum, and BILL Divvy.
Cards are already where business spending happens. Juniper Research estimates virtual card transactions at $5.2 trillion in 2025, rising to $17.4 trillion by 2029. It also expects 66 million corporate cards in use worldwide by 2030, up from 55 million in 2026.
And adoption is still growing. Many companies are shifting from traditional reimbursement workflows to corporate card programs with built-in expense tracking and spend controls.
When you’re evaluating the best corporate cards, the decision isn't about rewards.
You’re deciding how your company controls spending, tracks expenses, and connects transactions to accounting.
Best corporate cards compared (quick overview)
| Card | Best fit | Personal guarantee | Eligibility model | Issuance fee | Spend controls | Rewards model |
|---|---|---|---|---|---|---|
| Aspire | Global startups and new US entities needing an all-in-one finance platform | No | Secured corporate card2 backed by collateral deposit; no personal guarantee required | Free | Policy-based limits, unlimited virtual cards, granular merchant & transaction controls | 1.5% cashback^ on all spends |
| Ramp | Lean startups focused on cost control and automation | No | Requires significant company cash balance (often USD $25k+) and incorporated entity | Free (USD $0/mo/user); Plus: USD $15/mo per user; Enterprise: custom pricing | AI-driven spend insights, automated receipt capture, real-time expense monitoring | Rewards up to 5% savings and cashback across purchases |
| Brex | Venture-backed startups scaling rapidly | No | Cash-based underwriting; venture funding or strong bank balance typically required | USD $0/user/month; USD $12/user/month for advanced features. | Advanced spend analytics, automated policy enforcement | Tiered startup rewards (up to 7x rideshare, 4x travel) + partner perks |
| Amex Corporate Platinum | Executives and teams with heavy travel | Set by your employer’s program | Issued through the employer's corporate card program | USD $550 per year | Centralized billing and employee cards | Centralized billing and employee cards 1,550+ lounge access, $200 airline credit, $209 CLEAR+ credit, Global Entry/TSA PreCheck credit, 5% Uber Cash |
| BILL Divvy | Growing SMB teams needing strict spend controls | No | SMB-friendly qualification with budget-based card allocation | No annual fees | Budget-first card limits, team spend policies, approval workflows | Tiered rewards depending on payment schedule |
Facts checked on October 5, 2026, on each provider's site. Terms may change, so confirm on the provider's site before you apply.
What is a corporate card
A corporate card is a company-issued payment card used to manage spending across employees, teams, and departments from your corporate credit account.
The key difference from most business credit cards is liability.
Many small business credit cards ask the owner to sign a personal guarantee, so you can be held responsible if the company can’t repay. Liability terms vary by issuer and product, though. Some issuers offer company-only liability to established businesses, so check the cardholder agreement before you apply.
The corporate card program is usually underwritten, which means it is evaluated and approved based on your company’s financial profile rather than your personal credit history.
That changes the structure:
- The company typically holds liability for charges
- Employee cards can be issued under one program
- Your personal credit exposure is reduced
This separation between business spending and personal liability is one reason corporate cards have become popular with scaling companies. Modern corporate card platforms go further. Instead of acting as a simple credit line, they often include:
- real-time expense tracking
- receipt capture and policy enforcement
- accounting integrations with tools like QuickBooks or Xero
- spend controls across teams
In practice, the best corporate credit card becomes the spending layer of your company’s finance stack, giving you real-time visibility of where money moves across the business.
What to look for in best corporate credit cards
The best corporate card programs do more than pay for things. Use these six checks to compare them, from a 5-person startup to a large corporation.
1. Which corporate credit card has the best expense tracking tools
Look for a credit card that logs each transaction as it happens and asks the employee for a receipt right away through app notifications, email, or text. Aspire and Ramp both track spending in real time. Ramp also matches each receipt to its transaction automatically. Aspire also allows the admin and finance users one live dashboard for company spend.
For you, that means:
- fewer reimbursement requests
- faster month-end closing
- better visibility into where company money goes
2. Virtual cards and vendor-level security
Another feature that separates the best corporate card programs from traditional business cards is virtual card infrastructure.
Virtual cards allow you to generate unique card numbers for individual vendors, subscriptions, or employees. Each card can include its spending limits, expiration dates, and merchant restrictions.
Instead of sharing one company card across the team, you isolate spending for each vendor. If one vendor is breached, you cancel just that card, and every other payment keeps running.
With Aspire, Admin users can create virtual cards instantly and configure rules such as
- transaction count limits
- expiration dates
- merchant restrictions
3. EIN-based underwriting with no personal guarantee
The best credit cards for corporations often rely on the company’s financial health rather than personal credit, which allows you to scale company spending without tying it to your personal credit profile.
For founders, EIN-based underwriting creates an important separation between personal finances and business operations.
Aspire’s U.S. corporate card2 model (AFT Secured Commercial Charge Card) allows new entities to access corporate-level spend controls through secured cards backed by a collateral deposit. By funding a collateral account, you unlock an equivalent spending limit without relying on a high personal credit score.
That makes corporate-level spend management accessible even for newer companies entering the U.S. market.
4. Accounting integrations
A corporate card should function as an extension of your accounting system. Modern platforms integrate directly with tools such as QuickBooks, Xero, and NetSuite, allowing transactions to sync automatically into your ledger.
When purchases flow directly into accounting software:
- manual data entry disappears
- reconciliation errors drop
- financial reports stay current
With Aspire, you can integrate accounting platforms like QuickBooks and Xero, so your finance team reconciles transactions as they happen instead of waiting for month-end statements.
5. Rewards and corporate perks
Rewards still matter, especially if your company spends heavily on marketing, travel, or SaaS.
Some corporate card programs focus on cashback, while others offer startup-focused partner perks, such as software discounts or cloud credits.
For example:
- Flat cashback^: Aspire pays 1.5% on eligible spend
- Points by category: Brex pays 7x on rideshare and 4x on Brex Travel, and lists more than USD $350,000 in partner discounts (AWS, Slack, OpenAI)
- Travel perks: Amex Corporate Platinum includes 1,550+ lounges and up to $200 in airline fee credits
But in practice, the biggest value often comes from efficiency.
Time saved often matters more than rewards. A card that automates receipts and reconciliation can save your finance team more than an extra 0.5% back would earn.
6. Total cost, including FX
The most cost-effective corporate credit card options charge $0 for the card. The costs show up elsewhere:
- Per-user software fees: Ramp Plus is $15 per user per month plus a platform fee. Brex Premium is $12 per user per month
- Annual card fees: Amex Corporate Platinum is $550 per card
- Foreign transaction fees: charged on many cards when you pay in another currency or a merchant bills from outside the US. For the US, Aspire charges 0.22% above mid-market FX rates. Please mention those here if necessary.
Add these up for your real headcount before you compare rewards.
The 5 best corporate cards for US businesses in 2026
This list covers the top corporate credit cards for US companies in 2026. If you’re searching for the best employee credit cards, these are the programs to compare: each lets you issue cards to your team under one company account. They’re built for different stages, from a newly formed entity to a company with an executive travel program.
1. Aspire corporate card (best all-in-one finance platform)
The Aspire Corporate Card² is built for founders who want their card, US business account, and multi-currency tools in one place. It’s a secured corporate charge card on Mastercard, issued by Column N.A. Your limit matches your collateral deposit, so a new US entity can start spending without years of credit history.
Best for: global founders and new US entities Key facts: no personal guarantee, limit set by your collateral deposit, balance repaid daily from your Aspire account, USD $0 to issue cards
Pros:
- 1.5% cashback^ on business travel, online ads, SaaS tools, and more
- Unlimited virtual cards with merchant and transaction controls.
- Sync transactions with accounting software like QuickBooks and Xero.
Cons:
- Requires an upfront deposit to set the spending limit.
- Designed as a pay-in-full card; not suitable for carrying long-term debt.
2. Ramp corporate card (best for expense automation)
The Ramp Corporate Card is designed for companies that want automation to do most of the expense work. Ramp collects receipts by email or text, flags duplicate SaaS subscriptions, and enforces your spend policy before a purchase goes through.
Best for: finance teams that want to automate expense work
Key facts: no personal guarantee or personal credit check, USD $25,000 in a linked US business bank account, free plan $0, Plus - USD $15/user/month plus a platform fee
Pros:
- Cashback on every purchase, plus software that Ramp says can save up to 5% on total spend
- No personal guarantee or personal credit check is required
Cons:
- Generally, you need to have at least USD $25,000 in a linked business bank account
- Not available to sole proprietors or unincorporated businesses
3. Brex corporate card (best for venture-backed startups)
The Brex Corporate Card is built for venture-backed startups, with limits based on your company’s cash and funding rather than your personal credit. Capital One completed its acquisition of Brex in April 2026, and Brex now operates as a Capital One company. Brex underwrites on your cash position and funding, not your personal credit.
Best for: venture-backed startups
Key facts: no personal guarantee · US EIN, incorporation, and address required · Essentials USD $0, Premium USD $12/user/month
Pros:
- Tiered rewards focused on growth: up to 7x on rideshare and 4x on travel.
- Includes USD $350,000+ in partner perks (e.g., AWS, Slack, and Google Ads credits)
Cons:
- High cash balances (often USD $50,000+) are required to qualify
- Daily payment terms may apply for companies without significant funding'
4. Amex corporate platinum (best for travel perks)
The Amex Corporate Platinum Card is designed to be the best credit card for employees participating in a company corporate card program. It’s one of the top business credit cards with best corporate perks. It focuses on premium travel benefits and executive-level travel perks rather than startup-style spend automation tools. It's one of the best corporate credit cards for large businesses with an existing American Express corporate program.
Best for: travel perks
Key facts: Up to USD $200 a year in airline fee credits with one selected airline, up to USD $219 a year for CLEAR+, and up to USD $120 for Global Entry or USD $85 for TSA PreCheck
Pros:
- Access to the American Express Global Lounge Collection, providing complimentary entry to 1,550+ airport lounges across 500+ airports worldwide
- Premium travel perks such as up to USD $200 annual airline fee credit and CLEAR Plus membership credits
- Corporate program structure with centralized billing and employee cards
Cons:
- USD $550 annual fee
- Typically available only through an employer’s corporate card program, not as a standalone application'
5. BILL Divvy corporate card (best for SMB spend controls)
The BILL Divvy Corporate Card is a great option for small-to-mid-sized businesses that need rigid, budget-first controls for their teams. It uses a unique budgeting software where you assign funds to a card before the employee can spend, preventing overages before they happen.
Best for: best corporate credit card for small businesses that want strict budgets per team
Key facts: no personal guarantee · soft personal credit pull at application · credit lines from USD $1,000 to USD $5M · free software
Pros:
- The expense management software is completely free to use.
- Allows you to build business credit without necessarily needing a high revenue threshold.
- BILL also offers separate accounts payable and receivable tools, so you can pay bills, send invoices, and manage card spend in one platform.
Cons:
- Rewards are tiered; you only get the best rates if you pay your balance weekly.
- Underwriting may still involve a soft or hard credit pull of the business owner.
Corporate cards vs business credit cards
Corporate cards and corporate charge cards both help companies pay for expenses, but they operate very differently as spending grows.
| Corporate cards | Corporate cards | Business credit cards |
|---|---|---|
| Liability | Usually sits with the company, not the founder | Often requires a personal guarantee from the founder, though terms vary by issuer |
| Who spends | Built for spending by many employees, with centralized billing | Spending typically centers on the founder |
| Controls | Spend rules, approval workflows, and real-time tracking | Relies more on manual monitoring |
| Repayment | Typically pay-in-full charge cards | Usually revolving credit, with interest on any balance you carry |
| Best for | Scaling teams with higher monthly spend | Early-stage businesses and solo founders |
For a detailed breakdown of how the two models differ, see our full guide on corporate cards vs business credit cards.
Which corporate card is easiest to qualify for
Aspire may be easier to qualify for if you can fund a collateral deposit, because the deposit sets your limit instead of your revenue or funding. BILL Divvy uses a soft credit check, and its credit lines start at USD $1,000. Ramp, Brex, and Amex look for more cash, funding, or company size.
| Card | Minimum to qualify |
|---|---|
| Aspire | Collateral deposit that sets your limit |
| BILL Divvy | Credit underwriting; lines from $1,000 |
| Ramp | $25,000 in a linked US business bank account |
| Brex | $50,000 cash (funded startups), $500,000+ revenue, or a referral |
| Amex Corporate Platinum | An existing Amex corporate program at your employer |
For a wider list, including business credit cards, see our guide to the easiest business credit cards to get.
Benefits of corporate card programs
Moving from manual reimbursements to a structured corporate card program changes how companies manage spending.
1. Real-time expense visibility
Corporate card platforms record transactions the moment they occur. Finance teams can see company spending instantly instead of waiting for monthly statements, making it easier to monitor burn rate and identify unusual transactions early.
2. Faster expense reconciliation
When transactions and receipts are captured immediately, reconciliation becomes much simpler. Finance teams spend less time chasing documentation and can close the books faster at the end of each month.
3. Better employee spend control
The best corporate cards allow employees to make necessary purchases without using personal funds. Finance teams maintain oversight by setting spending limits and monitoring activity across the organization.
The multi-card strategy smart founders use
As your business grows, a single company card quickly becomes a bottleneck. Smart founders solve this with a multi-card strategy or credit card stacking.
Instead of routing all expenses through one of the best corporate credit cards, they create dedicated cards for different spending categories.
A typical multi-card structure would be:
- Infrastructure Card: Dedicated to AWS, cloud services, and developer tools.
- Marketing Card: For digital ads (Google/Meta), creative software, and campaign platforms.
- SaaS Card: For recurring subscriptions like Slack, Notion, or analytics tools.
- For flights, hotel
- Travel Card: For flights, hotels, and team-related expenses
How founders set up a multi-card strategy
- Confirm you meet the qualification criteria: Most multi-card strategies require strong credit (typically a credit score in the 680 to 700 range), a positive credit history, low credit utilization, and stable income.
- Prepare before applying for cards: Review your credit reports and plan your applications carefully. Many founders apply for several cards within a short period to avoid issues with lenders that are sensitive to multiple recent credit inquiries.
- Apply for cards with different purposes: Choose cards based on how your business spends money.
For example, founders often use 0% APR (annual percentage rate) cards for short-term financing; cashback cards that return a percentage of spending for marketing or SaaS expenses; and corporate cards like Aspire to manage operational spending and employee expenses.
- Access and organize your credit lines: Once approved, each card provides its credit limit. Together, these limits create a larger pool of available capital that can be used across different areas of the business.
- Assign each card to a spending category: Many founders structure cards around operational needs, so spending remains organized, such as designating one card for marketing expenses, another for supplies, and a third for travel costs.
- Manage balances and repayments carefully: Track each card’s balance and payment schedule. Paying balances before interest accrues helps maintain credit health and prevents the stacking from becoming expensive.
This is why modern corporate card platforms focus on virtual cards and spend policies, not just credit limits.
With the Aspire Corporate Card, founders can generate unlimited virtual cards, apply specific spending rules, and monitor all activity from a centralized dashboard.
The result is a finance system that stays organized and scalable as you grow, rather than becoming chaotic.
Frequently Asked Questions
In most corporate card programs, the company is liable for the charges, not the employee using the card.
Cards are issued under a central company account, and employees spend within limits set by the finance team. This structure allows companies to issue multiple cards while keeping liability and repayment responsibility with the business.
Corporate cards usually do not affect your personal credit if they are underwritten based on the company’s finances.
Many providers evaluate the business using its EIN, revenue, or cash balance instead of the founder’s personal credit score. If a card requires a personal guarantee, however, missed payments could still impact personal credit.
If you cannot qualify for a traditional corporate card, you may still access secured corporate card programs.
These cards tie the spending limit to a company deposit or bank balance. Businesses can also start with a business credit card while building financial history before upgrading to a corporate card.
Corporate credit cards can have stricter qualification and repayment structures than traditional business credit cards.
Many operate as charge cards, meaning balances must be paid in full each billing cycle. Some providers also require minimum revenue levels or strong cash balances to qualify.
Revenue requirements for corporate cards vary by provider.
Traditional corporate card programs may require USD $1M or more in annual revenue, while many fintech platforms approve companies based on cash balances starting around USD $25K–USD $100K.
A personal guarantee is a legal promise that the business owner will repay company debt if the business cannot.
Many traditional business credit cards require a personal guarantee tied to the founder’s social security number and credit profile. Some modern corporate card programs remove this requirement by underwriting the business directly.
Corporate cards and business credit cards are not the same, although both are used for company spending.
Business credit cards usually require a personal guarantee and rely on the owner’s credit score for approval. Corporate cards are typically underwritten based on the company’s financial profile, offering stronger spend controls and centralized expense management.
Yes, some startups can qualify for corporate cards, especially through fintech providers that evaluate cash balance instead of revenue history.
Many modern corporate card platforms approve companies based on available funds in the business account rather than years of operating history. Some also offer secured corporate cards, where the spending limit is tied to a deposit or bank balance.
Sources
- https://www.juniperresearch.com/press/virtual-card-transactions-to-soar-globally/ (https://www.juniperresearch.com/press/virtual-card-transactions-to-soar-globally/) - March, 2025
- https://help.aspireapp.com/us/en/articles/11388350-guide-to-creating-virtual-corporate-cards - March 09, 2026
- https://aspireapp.com/us/corporate-card - March 09, 2026
- https://ramp.com/blog/corporate-credit-card-program#Consider-Ramp's-modern-corporate-card - March 09, 2026
- https://ramp.com/pricing - March 09, 2026
- https://ramp.com/corporate-cards - March 09, 2026
- https://www.brex.com/product/credit-card - March 09, 2026
- https://www.nerdwallet.com/business/credit-cards/best/corporate - January 06, 2026
- https://www.americanexpress.com/en-us/business/corporate/cards/platinum-card/ - March 09, 2026
- https://www.bill.com/product/credit - March 09, 2026
- https://ramp.com/blog/business-credit-card-statistics-and-metrics - August 06, 2025
- https://www.brex.com/support/brex-account-requirements - March 09, 2026
- https://help.bill.com/direct/s/article/2825 - March 09, 2026
- https://www.brex.com/spend-trends/corporate-credit-cards/credit-card-stacking - March 09, 2026
- https://www.americanexpress.com/en-us/business/corporate/more-corporate-cards/platinum-card/ (https://www.americanexpress.com/en-us/business/corporate/more-corporate-cards/platinum-card/) - Oct 9th 2026
This blog is for general information only and does not constitute financial, legal, tax, or professional advice. Aspire’s services are subject to the terms outlined in our ’Terms of Service’ and ’Pricing’ pages. We make no guarantees as to the accuracy, completeness, or timeliness of the content, and past results do not indicate future performance. Always consult a qualified professional before acting on any information provided.
Content Team
Aspire editorial
Content team at Aspire is a society of seasoned writers & experts specialising in finance, technology and SaaS space. With 50+ years of collective experience, they help make business finance more profitable for readers. They write about finance tools, finance insights, industry trends, tactical guides to grow your business & also all things Aspire.
Aspire Launchpad
Supercharge your finance operations with Aspire
Find out how Aspire can help you speed up your end-to-end finance processes from payments to expense management.
Latest articles
QuickBooks vs Xero: Key differences, costs and which is better
QuickBooks vs Xero compared on features, pricing, users, reporting, and ease of use. See which accounting software is a better fit for your business.
How general liability vs professional liability insurance works in the US
Small business guide to general liability insurance. Learn about costs and coverage, if you need it, and how to choose the right policy.
Best multi-currency business accounts in the US for 2026
Compare the best multi-currency business accounts in the US for 2026. Explore fees, FX costs, currencies, holding, receiving options, and key features.